Unknown's avatar

About Agmoos

I am a journalist writing primarily about agriculture for various newspapers over the past 30 years...and before that, I milked cows and tended calves and heifers. I am also a mother and grandmother with three grown children: A teacher, restaurateur and homemaker. Our two sons and one daughter all like to cook and they are food conscious... not paranoid. My "foodographic" Agmoos blog is a place to find stories and photos of the people and places behind the food we eat and for commentary and analysis on food, farm and marketing issues facing producers and consumers.

Government is the problem, cows are the solution

By Sherry Bunting, Farmshine, September 29, 2023

WASHINGTON – Several important amendments aimed at limiting USDA and FDA powers in the administration’s climate agenda, nutrition mandates, even an amendment on checkoff transparency, peppered the hotly debated FY2024 Ag Appropriations bill in an overnight marathon at the end of September as House of Representatives worked to avoid a government shut-down Oct. 1.

Some amendments passed and others failed.

Perhaps most notable was the Spartz Amendment (76) related to commodity checkoff transparency. It passed on a voice vote in the near midnight hour Sept. 26, but a recorded vote was requested by the opposition, and it was soundly defeated 326 to 72 in the late afternoon on Wednesday.

Here’s what we’ve learned from C-SPAN coverage and other sources about key agricultural amendments that are included and excluded.

The defeated Spartz Amendment would have prohibited use of taxpayer funds to carry out, administer or oversee the 22 commodity checkoff programs.

Other amendments that succeeded would prohibit USDA’s use of the appropriated funds to carry out the administration’s “climate agenda” via a long list of executive orders. Some amendments that passed prohibit USDA’s use of appropriated funds to enforce certain school meal rules, such as a proposed to ban chocolate milk in elementary schools and the current 14-year ban on whole milk at all grade levels.

A half-dozen amendments targeted specific USDA and FDA bureaucrat’s salaries by using the Holman Rule to cut down to $1 the salaries of, for example, the USDA Food Nutrition Services deputy under secretary for her role in expanding SNAP eligibilities beyond congressional intent and in expanding USDA diet-police tactics in schools by implementing the whole milk ban from a la carte offerings in 2012.

On the failure side, in addition to the Spartz amendment, another amendment offered by Wyoming Congresswoman Harriet Hageman would have undone the USDA mandate for electronic cattle identification. It would have left the funding in place for farmers and ranchers wanting to use the electronic ID (EID) system, but would have removed the mandate language.

Said Hageman: “Ireland required this. Today, a year later, there are untold numbers of reports they must fill out for the government, and Ireland now is considering killing off 1.3 million head of cattle to reach their ‘climate targets.’ Their EID mandate will help them carry out this slaughter.”

She said mandatory EID “will cost ranchers millions in compliance cost, causing smaller farms to sell out and accelerating vertical integration so the farmers and ranchers will be nothing but serfs. This is supported primarily by the four big packers — two of which are owned by Brazil and by China.

In opposition to the EID amendment, Chairman of the House Ag Committee, Glenn G.T. Thompson (R-Pa.), said technology and innovation are needed to protect livestock agriculture from disease outbreaks.

On the Spartz checkoff amendment, Thompson said the place to handle this is in the farm bill, not appropriations.

In defense of her approps amendment, Indiana Congresswoman Victoria Spartz said: “I am a farmer, and my cosponsor is a farmer, and we want to stand with the farmers.

“Farmers used to pay a checkoff voluntarily to promote the commodities. Then Congress made it mandatory, and there is no transparency,” she said. “If you are going to force farmers to pay the money, they should know where their money goes. Do they promote commodities? Or do they promote very wealthy jobs?”

She explained further that her amendment had two parts. One calls for checkoff transparency language in the farm bill. The other sought to be included in the Ag Appropriations, simply stating that no taxpayer funds can be used to carry out or oversee checkoff programs.

“It’s a simple amendment, but the special interests have gone on the attack saying: ‘How can Congress ask us what we’re doing with the money?’” said Spartz. “Now it has become imperative since they are now lobbying with this money against this amendment and against transparency.

“They say they aren’t using taxpayer money… So, just clarify this to Congress — that no taxpayer dollars are going to these boards that who knows where they spend the money,” she explained.

Cosponsoring the amendment, Rep. Tom Massie of Kentucky said: “This program has gone rotten and no longer serves farmers. In fact, we just sent a bipartisan letter to Secretary Vilsack reminding him that the USDA is required to report annually to Congress on the disbursement of these funds and show a third-party audit of their effectiveness.”

Massie noted that these reports to Congress have not been filed since 2018 for dairy, during which time dairy farmers paid over $1 billion, and more than 6000 have gone out of business.

Thompson stressed that the debate on checkoff transparency “should be reserved for the farm bill, not appropriations.” He said taxpayer funds are not being used in checkoff programs nor to oversee them.

Thompson expressed caution that some recent challenges to checkoff programs can be a veiled attack by animal rights groups that see this as an opportunity to weaken livestock agriculture. He said the farm bill is the place, “where conversations are already occurring, to improve these programs, to refine them, and to make them more transparent. I see the farm bill process as the appropriate path forward for achieving this transparency.”

“They should already want to be transparent to show this great thing they do for farmers,” Spartz countered. “But they are serving large monopolies, contributing to more consolidation so the little guy cannot survive.”

Spartz noted that Congress should “not be afraid to challenge these programs… to be the lobby for the people.”

For the three days leading up to the vote on the Spartz amendment, many agricultural groups with close ties and joint programs with commodity checkoff organizations amassed a barrage of lobbying efforts in opposition.

National Milk Producers Federation and National Cattlemen’s Beef Association spearheaded these efforts, including a letter signed by 130 organizations, saying that the Spartz amendment “unfairly targeted ‘producer-led’ checkoff programs that only use funds collected from proceeds of sale of these commodities – not taxpayer funds.

Here’s how I see it… If that premise is true, then what are the lobbyists opposing it so afraid of? No foul, no harm, right?

Perhaps they are afraid of the auditing that may be required to prove to Congress that no taxpayer funds are used to carry out checkoff programs. In fact, at the 11th hour, the Ag Environmental Coalition signed on to the letter opposing the Spartz amendment that was sent broadly to congressional offices urging a ‘no’ vote.

Could it be that taxpayer funds in the USDA coffers are being coughed up to further so-called ‘net-zero’ pathways initiated by the national dairy checkoff via DMI and its various tentacles?

It was USDA Secretary Vilsack, himself, who was first to announce Dairy Net Zero while testifying to the U.S. Senate in 2019 — asking them to fund Net Zero pilot programs. At that time, he was employed by checkoff, pulling down a million dollar salary via checkoff.

Now, Net Zero is the centerpiece of DMI’s “U.S. Dairy transformation” and the USDA ‘climate agenda’.

In fact, during a debate on an amendment offered by Florida Congresswoman, Kat Cammack, she cited a recent report citing Vilsack’s coordination with Arabella Advisors, a Soros-funded group, on “transforming the U.S. food system.”

She said the U.S. “can’t produce and process food for this country and abroad if we can’t rely on fuel and food systems not to be hijacked by the extremest climate agenda” and noted “many of these radical things do more harm than good to our environment. Our farmers and ranchers are the best in the world, and this amendment prevents the Biden administration from pushing its climate initiatives. It safeguards farmers and ranchers from these misguided policies.”

Could there be some blurred lines between taxpayer and checkoff funds piled into the climate-smart wheel-of-fortune?

Is there some leakage of taxpayer funds into certain checkoff industry structures and pre-competitive proprietary partnerships that create winners and losers among farms, among processors, among regions?

Certainly, Secretary Vilsack’s salary has been drawn from two pockets over the past 15 years (taxpayer, then checkoff, then taxpayer). This raises eyebrows as do the shared pathways to the same destination (net-zero) being paved with funds from both pockets. Each may fund a different track, but moving in unison to the same destination: putting the cow in the loser column so that Big Food and Big Tech can collect Big Money with the tools to move her over to the winner column (temporarily, folks, because cows don’t stop belching).

The way I see it, DMI and its many tentacles have charted a path for dairy that deems the cow a loser while developing the pathway to be her savior — to turn her into a winner and then tell her story. They promote the RNG projects, feed additives and sustainability practices that reduce her natural methane emissions, but forget to promote the fact that

With or without these pathways to Net Zero, the cow is already a winner! Cows are not the problem! A cow’s global warming potential (GWP) is not new, it is a constantly recycled baseline in a natural biochemical cycle that is as old as life itself. Math matters here!

Meanwhile, some of the checkoff-promoted tools deemed to make her loser-methane a “winner” will actually consolidate the dairy industry even more rapidly.

Large new production sites hinge on huge Renewable Natural Gas (RNG) projects that hinge on lucrative renewable fuel credits. Each permit recorded over the past two years and forward for the next five equals 2500 to 10,000 cows in expansions and new dairy sites.

These operations are less dependent on the level of the milk price to cash-flow, and they are bound by contracts to milk large numbers of cows to produce quantities of methane to then offset via RNG production to then generate credits for the exchanges.

At the federal milk pricing hearing in Indiana, we have heard processors lament that the FMMO minimum prices are too high. They’ve said the proof is the negative premiums and dumped milk this summer.

Are they really looking at getting the milk price minimums low enough that they can pay for those large new and expanded farm methane credits for their own scope 3 portfolios? Some processor testimony has mentioned sustainability costs in the make allowance part of the FMMO hearing. Do they want to weaken FMMO uniform pricing so they can cut farms that don’t measure up and use creative methane math to buy credits from others via milk premiums built on lower FMMO minimum prices?

We even have a global processor in New York State already doing a ‘pilot’ right now to monitor methane by analyzing their shippers’ Dairy One milk test data to benchmark farm methane emissions and make “recommendations.”

There’s a lot of money to be made by keeping cows in the loser column, and then building the consolidated pathways to move her into the Net Zero winner column.

Unfortunately, the math doesn’t add up, and the real losers will be our beloved cows – foster mothers of the human race — and our children and grandchildren who are already deprived of the very best our cows have to offer during 2 meals a day, 5 days a week, 9 months a year at school.

Farmshine editor and publisher Dieter Krieg hit the nail on the head in his editorial in the September 22 edition. The anti-animal agenda is real, and that fox is has been inside our henhouse with an agenda that began in 1995 when DMI was created to manage both halves of the checkoff structure, and it has become more obvious since 2008, when the Innovation Center for U.S. Dairy was created. This is also the year the whole milk ban train started rolling and DMI began conspiring with USDA to “advance the dietary guidelines” via a memorandum of understanding that initiated GENYOUth.

We’ve reported extensively on the murky methane math, the ten-fold typographical errors, the worsening dietary guidelines that ignore science, and the progressively more restrictive fat rules for school meals that are now morphing to anti-cow climate considerations.

More recently, we’ve reported on how the bubble-up in milk production in the Central U.S. that led to dumping of milk and unforeseen disastrous prices this summer was largely fueled by new RNG projects like are promoted by checkoff to help our very-bad, no-good cows become good for the planet.

The misappropriation of math and science has been staggering. Government is the problem, not the solution. Cows are the solution, not the problem. Newsflash: cows are already good for the planet, and they provide us with optimum natural nutrition we enjoy.
Federal milk price hearing heats up over ‘make allowances’ and Class I ‘mover’

Farmers testify, Farm Bureau stands firm, USDA asks good questions, wants to hear from farmers

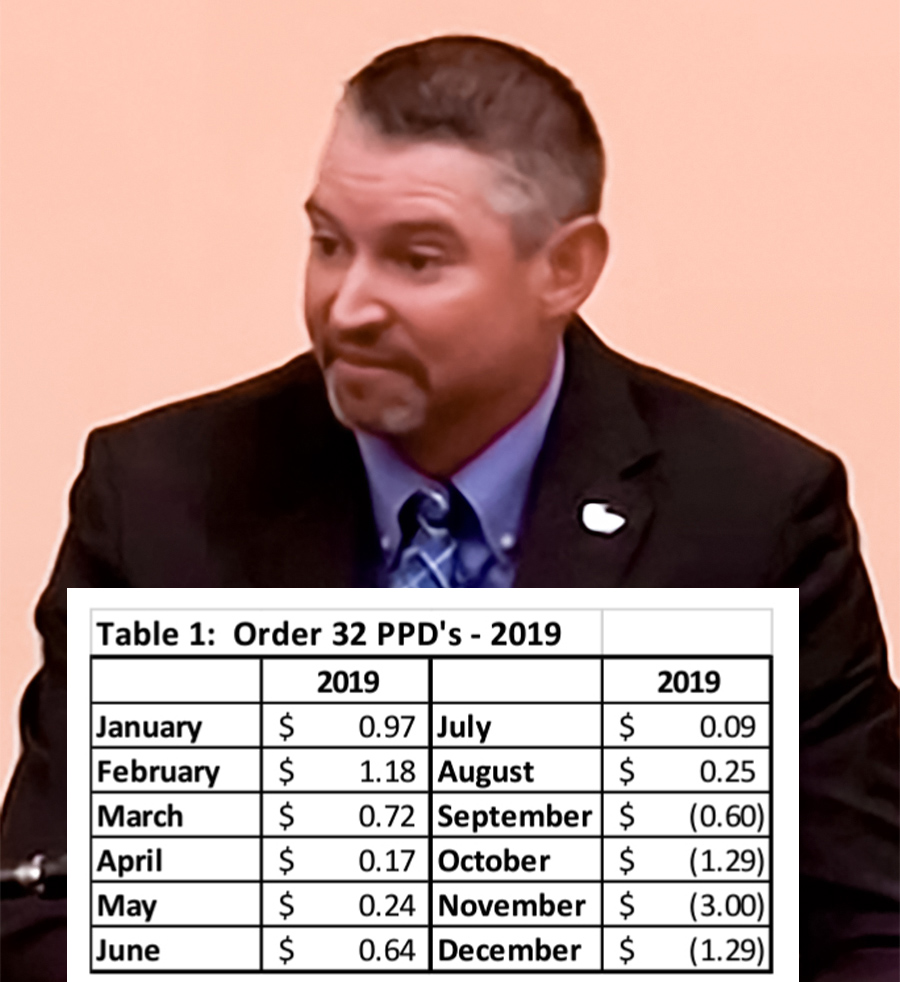
Bryan Henrichs, an Illinois dairy farmer, included a chart in his testimony showing these PPD swings in his milk marketing area (Order 32) from January through December 2019, before and after the Class I mover change — a year BEFORE the pandemic hit. 

Sherry Bunting, Farmshine, September 22, 2023

CARMEL, Ind. – The controversial “make allowances” took center stage for the past 10 days at the USDA federal milk price hearing in Carmel, Indiana. Witness testimony and attorney cross examinations — as well as follow up questions by USDA staff — have been particularly revealing. To-date there are nearly 300 exhibits, and the hearing is two-thirds of the way through its 21 proposals in five categories. The hearing can be followed daily at the live stream link: https://www.zoomgov.com/j/1604805748&nbsp

American Farm Bureau Federation economists Danny Munch and Roger Cryan have been exemplary in the way they are bringing their grassroots policy to the USDA hearing setting and standing up to heavy cross examination by attorneys for the processors as they seek to undermine AFBF’s position that no make allowance increases should be granted by USDA without a mandatory, audited cost survey, and that the Class I mover should go back to the ‘higher of’ calculation.

Entering its fifth week on Tues., Sept. 19, the emphasis has shifted to the various proposals on how to calculate the Class I base price ‘mover’ – whether to return to the ‘higher of’ or to use one of several proposals from processor groups that want to keep the ‘average of’ method but propose complicated ‘look-back’ adjusters to incrementally ‘pay back’ future Class I value losses incurred by farmers over a distant multi-year time frame.

Last Friday, September 15, several dairy farmers testified. In this week’s hearing update, we’ll focus on one farmer’s illustrative testimony in support of National Milk Producers Federation’s proposal 13 to return to the ‘higher of’ for the Class I mover calculation. 

While several testified, it was dairy farmer Bryan Henrichs, of Breeze, Illinois who best described the impact of the Class I mover change made legislatively five years ago on farmers’ ability to do risk management and on the FMMO mandate for ‘orderly marketing’ and service of the Class I fluid milk markets.

“With some classes having the ability to depool, this has created disorderly marketing as there isn’t the incentive to serve the Class I market,” said Henrichs. “I am unable to have my cooperative depool my milk due to my milk serving the Class I market. I have heard from some in the industry that the negative Producer Price Differentials (PPDs) (and resulting losses to dairy farmers) were caused by the USDA food box program.  I would disagree as the negative PPDs began not too long after the industry moved to the ‘average of’ in May 2019.”

Henrichs operates a 300-cow dairy farm, is on the Prairie Farms board, the American Dairy Coalition board, and was part of the American Farm Bureau Federation (AFBF) dairy task force. He saw first hand the devastating consequences to farmers from the Class I pricing change.

Henrichs included a chart in his testimony showing these PPD swings in his milk marketing area (Order 32) from January through December 2019, before and after the Class I mover change a year before the pandemic hit. 

He noted the industry has well documented the severity of losses much larger than this during the 2020-21 pandemic as well as the continuation of Class I value losses and depooling to farmers, even when it doesn’t show up as negative PPD — when Class IV is higher than Class III as has been the case in 2022 and 2023.

Henrichs expressed appreciation to USDA for the Pandemic Market Volatility Adjustment Program (PMVAP) payments that were aimed at covering just a fraction of these losses.

However, Henrichs duly noted the problem with “support” after-the-fact and the problem with “rolling adjusters” that try to make up for these losses later. They don’t help much if the large losses — the large negative basis that can’t be managed — hits cash flow so hard that farms are out of business by the time it’s “made up” to them and then only “made up” partly or quite gradually.

“I know some dairy producers that needed that money at that time — not 12 to 18 months later. I know of some that are no longer in business when they received the (PMVAP) payments,” said Henrichs. “The ‘higher of’ will ensure that the dairy producer is compensated at the time of the sale instead of later by some other form of support… and I worry if the USDA will always have the funds to provide such support.”

Henrichs pointed out that risk management doesn’t help in this scenario.

“We have used risk management tools in the past such as forward-contracting and DRP to help manage the price volatility of the dairy markets. With the ‘average of,’ we see the higher level of negative PPDs, which acts as ‘negative basis’,” Henrichs testified.

“We are familiar with ‘negative basis’ with corn as that indicates what the market values the commodity at the time of sale. At least with corn, I can call the elevator and find out what the basis is and decide if I want to ship to market,” he explained, adding that as dairy farmers, “we produce and ship a perishable product. With a negative PPD, we don’t know until two weeks after we are done shipping for the entire month whether or not there is a negative basis.”

Henrichs noted that he was shown a check from a neighbor who forward contracted in July 2020. 

“He shared with me his check as he locked in $18.00/cwt. milk in a Class III futures contract. He lost on the futures contract — as he would expect when the market rises — but due to the negative basis or negative PPD, he ended up with a net check of around $9.00/cwt. I continue to evaluate the amount of negative PPDs since going to the ‘average of,’ and I am reluctant to use forward contracting or DRP as part of my farm’s risk management program,” said Henrichs.

He stood his ground as attorney Steve Rosenbaum for IDFA made several attempts to trip him up on cross-examination. Rosenbaum tried to ‘cherry pick’ a few months in 2019 when the ‘average of’ yielded a slightly higher Class I mover compared to what it would have been under the ‘higher of.’

Henrichs’ matter-of-fact answers left the IDFA attorney unable to break him down. Rosenbaum asked if Henrichs had done monthly analysis of the ‘average of’ vs. the ‘higher of’ to see the months when it was positive. Henrichs replied: “Yes, we’re always watching.”

“No one questions, obviously, that when it comes to 2020 and the pandemic, Class III and IV started diverging substantially, and you ended up with less… but do you agree with me that until that happened, you weren’t experiencing this kind of ‘anomalous’ result, were you?” queried attorney Rosenbaum for IDFA.

“Not at that point, but once we started receiving the negative PPDs, they got extremely large, as you can see,” Henrichs replied, referring to Table I in his testimony. “It was way more of the negative than what the positives were prior to that.”

(Table I shows the PPD in Order 32 for all 12 months of 2019 — before and after the Class I formula change, which was implemented in May of 2019. This was a year before the pandemic. In fact, going forward it is still “way more negative than positive.” Farmshine has also been watching this accumulation of over $1 billion in cumulative net losses to farmers across 53 months, a graph that has been updated and published several times in Market Moos.)

Erin Taylor, acting director of USDA AMS Dairy Programs, questioned Henrichs about risk management: “So is this ‘negative basis’ the reason you are not using risk management tools currently?”

“Yes,” Henrichs replied, adding that, “as a custom operator putting silage up for a lot of dairy farmers, a lot of questions on dairy pricing get sent to me. We’ve had producers that bought DRP contracts, and in the months of April, May and June 2020, they were set to receive a pretty large sum, but because of depooling, with around a $20 to $21 Class III price in June of 2020, farmers in our area — because of  depooling — were unable to receive that (higher price) in their milk checks, but they were also not able to receive the DRP payments that were set to come to them. 

“They were kicked out because the price on the futures was higher than their contract that they purchased – that they bought for an $18 coverage for example – well that $20 (Class III price) kicked them into being above that ($18) they purchased, and they didn’t get a payment. So, even though on the Board of Trade, they may have looked good, that’s not what we received on our dairy farms,” Henrichs shared.

“Because that Class III milk wasn’t pooled?” Taylor picked up his the thought train in the form of a question.

“Yes, In Order 32 only 6% of Class III milk was pooled that month, so our price was around $12 to $13 per hundredweight for our dairy farms, but their contract for ($18) was set to pay them but did not because of that $20 Class III price on the Board of Trade (which became the announced FMMO price that led to Class III depooling).” 

(Put simply: That higher price the DRP contract ‘saw’ meant no DRP payment for the farmer, but that price wasn’t realized by the farmer. This is similar to having your barn burn down, and your insurance adjuster saying ‘well, because your neighbor’s barn didn’t burn down or something on paper says your barn should not have burned down, you are not entitled to a payment for your barn that in fact burned down.)

Taylor also asked what disorderly marketing looks like to dairy farmers. Henrichs gave perhaps the best explanation yet on this hearing record. He explained how the upside-down pricing — the misalignments that have been brought on by the switch from ‘higher of’ to ‘average of’ — caused pooled farmers to have ‘uniform prices’ vastly different within miles of each other due to depooling incentives on some Orders.

“Going back to the months of June 2020, and July, we saw large Class III prices, whereas in the ‘average of’, we saw Class I and Class IV were much lower, and you had farmers in Wisconsin, in Order 30, getting $4 a hundredweight more per the FMMO website, on the uniform price. We have producers that are within miles of 30, shipping in FMMO 32, who were $4 different, and their milk was being produced not far from each other. That’s disorderly marketing in my opinion,” said Henrichs.

“When you have guys not wanting to go to a Class I plant because the Class III price is so much higher, that is what I consider disorderly marketing — where you would have people jumping in and out of which product they want to sell their milk to that day because of the pricing disparity amongst the classes. Part of the class pricing in the FMMOs are to stabilize pricing to producers in each Order to be pretty similar.”

“So you’re saying that you see class prices being in typical historical alignment as orderly?” asked Taylor.

“Yes,” said Henrichs.

“Because then the incentive is there to service the Class I plants?” Taylor asked further.

“Yes, service the Class I first… make sure those are full for the fluid industry because they’re not able to store product like the powder and cheese plants,” Henrichs added.

Throughout this hearing, attorneys for IDFA and Milk Innovation Group scoffed at the idea that Class I plants could have any trouble getting milk for fluid use because the country has more than enough milk to go around. 

They avoided the question of what does it cost or how do they attract the milk to the Class I plant when the historical alignments are out of whack. 

They put forward witnesses from very large international processors saying that the FMMO minimum prices are set too high, that they must be lowered by raising make allowances and keeping the ‘average of’ mover and cutting Class I differentials and all sorts of changes. 

They pointed to the dumping of milk this spring in the Central U.S. as proof that FMMO minimum prices are set too high and must be lowered so that processors can pay premiums if they want to and can invest in plant capacity to soak it up so it doesn’t go to the sewer.

USDA’s Taylor went so far as to ask these processor witnesses what other factors affected the milk dumping this spring, what other factors affect milk production growth (in the Central U.S.). 

Processor witnesses stammered around on these capacity and innovation questions. They weren’t sure how to answer some of the very direct USDA questions over why they are so fast to make sure every bit of their cost is covered in that make allowance and yet balk at the idea of being asked to account for more of the pricing or value side.

Henrichs is just one example of farmers who are testifying in person on various days or virtually via Zoom on Friday afternoons. It is obvious that USDA AMS personnel want to hear from farmers – what they have to say, how all of this affects them. 

Farmers are the only ones who can show up at the hearing venue on any day, let an official know they are there to testify, and be worked into the schedule without sending written testimony or notice ahead of time. USDA merely asks that farmers bring their written testimony with them and make copies to hand out.

Virtual testimony must be pre-registered, but in-person testimony can happen any day.

Those farmers wanting to testify virtually have one more scheduled opportunity on Friday, Sept. 29. To get one of the available slots for that day, go to the hearing page on Monday, Sept. 25 at noon to look for the signup link. Be quick about it, because last Monday, the slots for Sept. 15 filled up within less than two hours. If the hearing continues into October, go to the webpage on subsequent Mondays to sign up for any slots offered on subsequent Fridays.

The hearing page is at https://www.ams.usda.gov/rules-regulations/moa/dairy/hearings/national-fmmo-pricing-hearing


For technical difficulties, email FMMOHearing@usda.gov

USDA’s Taylor brings the department’s questions for every witness. She has done a noteworthy job of this, pressing industry witnesses for details and bringing the deeper levels of farmer testimony to the fore.

Remember, when this is all over, and the t’s are crossed and i’s dotted on a USDA final decision, farmers will vote ‘yes’ to accept these changes or ‘no’ to dissolve their Federal Milk Marketing Order. This means even if co-ops bloc vote for their members, the co-ops and farmers have the final say.

There is an obvious concern among some in the processing sector that the FMMO system could be dissolved. One may believe that processors want the FMMOs to end because more and more of the cheese and other dairy products are being manufactured and sold outside of the FMMO system and outside of the pooling process.

However, processors have an interest in seeing the FMMO system continue because they rely on the pricing data, the benchmarking, and a built-in make allowance. 

The existence of FMMOs and those announced prices actually settle Class III and IV milk futures on the CME. Even if processors hedge risk by using dairy product futures contracts — instead of the milk futures contracts — they still rely on the USDA price survey every week that yields an official weighted average price for the four FMMO commodities that are traded on the CME to come up with the weighted average price of those commodities at the end of each month to settle butter, nonfat dry milk, 40-lb block and 500-lb barrel cheese and dry whey futures contracts.

Some argue that the daily CME spot cash markets for these products could be simply used. However, just think what this would mean if the CME became the only market to look to for futures and cash. Milk doesn’t have a real cash market reported every day on the farmer or processing sides like beef and other commodities. 

Furthermore farmers ship milk for four to six weeks before ever knowing what they’re going to get paid for what they shipped, or what the basis is going to be. They can’t look at a market and make decisions. They can’t call an elevator. They can’t hold their product for a week or a month… or even a day.

-30-

FMMO hearing update: ‘We made it to the moon, we can figure out this little equation’

Milk pricing formulas and ‘make allowances’ can feel like rocket science, farmers point out the pitfalls in ignoring the impact of mozzarella and the rising costs on dairy farms. Georgia and California producers among those testifying on make allowances, along with economists, including Dr. Mark Stephenson

Previous FMMO hearing updates can be found here and here

By Sherry Bunting, Farmshine, September 15, 2023

CARMEL, Ind. — “It’s really simple. We made it to the moon back in the late 60s… if you tell me that we can’t figure this little (mozzarella) equation out, we got something wrong,” said Joaquin Contente, the son of Portugese immigrants and a lifelong dairy farmer near Hanford, California as he gave virtual testimony Friday, Sept. 8 during the ongoing USDA Federal Milk Market Order (FMMO) hearing in Carmel, Indiana.

Contente serves on the California Dairy Campaign (CDC) board, which is a member of California Farmers Union (CFU) and National Farmers Union (NFU) as well as Organization for Competitive Markets (OCM). His son and daughter today run the 1100-cow multi-generational dairy farm in California’s San Joaquin Valley.

“Mozzarella should no longer be ignored. This issue was raised in 2000, and the volume and demand have grown dramatically since then,” he said, referencing CDC’s proposal and citing USDA data showing mozzarella production last year was nearly 5 billion pounds while cheddar was short of 4 billion pounds, and all cheeses totaled just over 14 billion pounds.

“I represent myself and many other producers who are reluctant to step up and speak out in opposition to what is being said by milk handlers, out of fear of retribution,” he reported. “It is essential to include the largest cheese category – mozzarella. The volume has significantly exceeded cheddar, and the Class III price should be modified to reflect these market conditions.”

Contente noted comments about the change in the Class I base price from ‘higher of’ to ‘average of’ costing farmers $1 billion over four years’ time.

“This mozzarella issue, if you understand the formulas and yield factors, is costing dairy farmers more, annually, well over $1 billion — and that’s a conservative number I am using,” he said.

“We have situations where the milk price drops dramatically, 30 or 38%, so you have to look at this discrepancy going on over a couple of decades. Nobody is talking about it… you’ve got to be a little bit quiet about mozzarella because you don’t want to upset ‘the mozzarella people,’” said Contente, noting that mozzarella production is 12% larger than cheddar with very high yields. 

“There is information that needs to be collected, and that is the roadblock right now. It’s the largest category, and yet there is no reference to it, and the yields are so high that these cheesemakers are making product that they’re not getting charged for. It’s for free — off our backs,” he said. “We are in a system that requires price discovery of the uses of milk, and here we have the highest (volume of cheese) use in mozzarella, and we just turn the other way… why?”

The past two weeks of the daily 8 to 5 hearing sessions have been quagmired in the nuts and bolts of multiple proposals on what’s included or excluded from the pricing surveys as well as the corresponding make allowances as the hearing moved into its fourth week Wednesday (Sept. 13).

Like other producers testifying so far, Contente detailed the loss of dairy farms around him and the discrepancy between milk prices and cost of production leading to mass exodus of dairy farms currently. 

Economists from academia and from cooperatives later showed numbers revealing the hard reality that the farm-well for pulling out more processor investment money is running dry.

In fact, Contente pointed out that the processor make allowance cost surveys include “return on investment,” something he said is lacking for dairy farmers in their milk prices. This was corroborated in later testimony by Cornell’s Dr. Chris Wolf and DFA’s Ed Gallagher.

During Dr. Mark Stephenson’s testimony Tuesday (Sept. 12), we learned that the current voluntary make allowance cost surveys include “opportunity cost” for plant assets used to make the products included in the survey.

“As farmers, we don’t get a return on investment,” said Contente. (And the numbers put up by expert witnesses show farmers don’t get ‘opportunity cost’ either.)

In fact, Gallagher said it’s important for USDA to consider the impact of its hearing decisions on farmers because if they can’t reinvest in their operations, it affects the infrastructure, the lending and the farmers’ access to capital — putting the milk supply at risk.

While Contente’s testimony focused on the mozzarella proposal supported by CDC, CFU, NFU and OCM, he also voiced their opposition to any increase in make allowances for processors.

On the latter, American Farm Bureau Federation agrees. AFBF also opposes any increase in make allowances based on voluntary surveys without first seeing results of a mandatory and audited processing cost survey. 

AFBF’s chief economist Roger Cryan on cross-examination asked Contente if NFU opposes the make allowance increases due to the voluntary and unaudited nature of the cost surveys. “Yes,” was his response. “Very good,” said Cryan.

The IDFA make allowance proposal would reduce farm milk prices by $1.25 per hundredweight initially and even more down the road.

For Class I producers, the net result is an embedded make allowance deduct as large as $3.60/cwt at current make allowance levels, which could rise above $5.00 in a few years if the IDFA proposal is approved. 

This producer loss is embedded in the Class I price even though Class I processors are not even asked by USDA to provide their cost data. 

Georgia milk producer Matt Johnson testified in support of NMPF’s various proposals, which include returning to the ‘higher-of’ Class I base price and increasing the differentials. On the issue of make allowances, he said the NMPF proposal is preferred because it makes smaller adjustments.

“I understand that make allowances are an important aspect in determining Federal Order class prices, and from time to time, there is a regulatory need to adjust them,” said Johnson; however, “my milk price will go down when make allowances go up. I ask that when increasing make allowances, the Secretary consider the impact on dairy farm milk prices… and profitability. NMPF has proposed more modest changes to the make allowances, which are projected to lower farm milk prices by about $0.50 per hundredweight (not $1.25).”

During cross-examination, Johnson was specifically asked by USDA AMS administrator Erin Taylor to explain how the make allowances affect him as his farm’s milk goes mainly to Class I markets in Florida and the Southeast, not to manufacturing.

“It’s all negative,” he replied. “The make allowances are used in the prices used to figure the base Class I milk price. I don’t know who gets that draw, but for me, it’s all negative.”

In addition to CDC’s proposal to add mozzarella, American Farm Bureau defended its proposal to add 640-lb block cheddar and bulk unsalted butter, and NMPF defended its proposal to remove 500-lb barrel cheddar.

Several days of detailed accounting testimony were heard, and the kicker was when representatives for Leprino and IDFA stated that barrels should be kept in the survey as a ‘market clearing’ product that is ‘storable’, but that bulk mozzarella should not be added because it’s a higher moisture, fresh cheese, not storable like cheddar, making it a product that is not a ‘market clearing’ product. (This idea of ‘what is market clearing’ was further explored this week as needing a new definition now that there is no dairy price support program or government storage of dairy products).

Interestingly, in cross examination, we learned that barrel cheese — which Leprino and IDFA want to keep in the survey — is also a relatively fresh cheese, not all that different from bulk mozzarella, as only 4- to 30-day-old barrel cheddar is reported. 

At one point, cheese industry representatives suggested the spread between blocks and barrels is used to price ‘basis’ and to price exported products, while block cheddar is mostly used to price other cheeses. Witnesses indicated some processors use barrel movement to price cheeses, such as mozzarella.

Some expert witnesses contended that other products can’t be added to the FMMO pricing formula because they are not traded on the CME. AFBF’s Cryan retorted that the CME should not be running this show, and he noted that dry whey wasn’t traded on the CME until after it was added to the FMMO formulas.

In fact, CME futures hedging, CME cash spot markets and the risk management tools that use these exchanges were a contentious point. Some witnesses said USDA formula changes will ‘disturb’ risk management contracts, and must be delayed 15 additional months after a USDA final decision to avoid such disturbance. 

On a similar note, economist Dr. Stephenson, while providing academic processor cost survey information this week, was cross-examined by economist Dr. Marin Bozic for Edge cooperative. Bozic asked Stephenson if the disturbance of risk management practices would ‘fit’ his understanding of ‘disorderly marketing’.

Stephenson replied: “No… I am not sure hedgers or speculators should be first or foremost in the minds of FMMO personnel. That’s not what we are here to do.”

-30-

Part Two: What drove rockier road for 2023 milk prices? Manure. Imports. Concentration.

— Along with more imports and shifts in cheese production, major manure-driven expansion in cheese-heavy Central U.S. put pressure on region’s ‘disrupted’ processing capacity

By Sherry Bunting, Farmshine, Updated in reflection from original publication in July 7, 2023 Farmshine

EAST EARL, Pa. — What has driven the rockier road for 2023 milk prices? Many things, and manure may be top on the list.

In fact, we’ll cover the ‘manure effect’ in a future article. But are we beginning to see the methane wheel-of-fortune behave with the ‘cobra effect’? (The British government, concerned about the number of venomous cobras in Delhi, offered a bounty for every dead cobra. Eventually, however, enterprising locals bred cobras for the income.)

This happened with greenhouse gases in the past. It happened with a byproduct gas of making refrigeration coolant. In 2005, when the UN Intergovernmental Panel on Climate Change began an incentive scheme. Companies disposing of gases were rewarded with carbon credits, which could eventually get converted into cash. The program set prices according to how serious the environmental damage was of the pollutant. (Like making cow methane seem like new methane when it’s not). As a result, companies began to produce more of the coolant in order to destroy more of the byproduct gas, and collect millions of dollars in credits. This increased production also caused the price of the refrigerant to decrease significantly.

With this prelude, let’s look back in retrospect on what I reported in the July 7, 2023 Farmshine when milk markets were in a tailspin hitting their low for the year — just 10 days before the gradual turnaround began.

As losses in the CME spot cheese markets and Class III milk futures markets continued through July 6, the Federal Order benchmark Class III price for June was pushed down to $14.91 per cwt. and protein down to $1.51/lb, July and August futures went well below the $15 mark, with Class III below $14.

Let’s look at the supply side of the January through June 2023 supply and demand equation.

Looking at the May Milk Production Report that was released in June, it’s hard to believe the bearish response we saw in milk futures and spot cheese markets that occurred based on a mere 13,000 more cows nationwide that month. It was a paltry 0.1% increase over a flat 2022, along with 11 more pounds of milk output per cow for the month (up 0.5% over flat 2022).

This flipped the switch from a gradually lower-than-2022 market to one that plunged sharply and suddently into the dumps – and all the analysts said: ‘We’ve got too much milk for demand.’ (In fact, two months later, processors are pointing to June and July milk dumping and $10 under class spot milk price as proof that USDA is setting Federal Milk Marketing Order minimum prices too high! — I digress).

As noted in Part One of this series that was published in the june 30 edition of Farmshine, other converging supply-and-demand factors plagued cheese markets that month until July 17 — despite basic fundamentals of these milk production reports not being all that bad. 

USDA Dairy Market News said spot loads of milk were being discounted in June by as much as $11 below the already abysmal FMMO Class III price in the Midwest. The milk dumping that reportedly began in May in Minnesota moved into Wisconsin through June and into July. The July 5th Milwaukee Journal Sentinel reported “Truckloads of fresh farm milk have been flushed down the drain into Milwaukee’s sewer system recently as dairy plants, filled to the brim, couldn’t accept more.” The story notes this had gone on for weeks, and the amount has declined to 5 trailer loads per week by the time The Milwaukee Journal Sentinel published its report.

For the price and milk dumping fallout, economists and analysts blamed the higher milk production (though it was modest on a national basis but huge in the Central U.S.). They blamed the higher cheddar cheese production (not accompanied by higher inventory), and they blamed the lower volume of exports (modestly below year ago on a year-to-date solids basis). 

Globally, milk production was up (it is declining this fall), they said, suggesting U.S. prices needed to get below the falling global prices in order to recover more export volume (instead of dumping in the sewer). Well, they got what they wanted as the U.S. prices dropped like a rock through June until the turnaround on July 17.

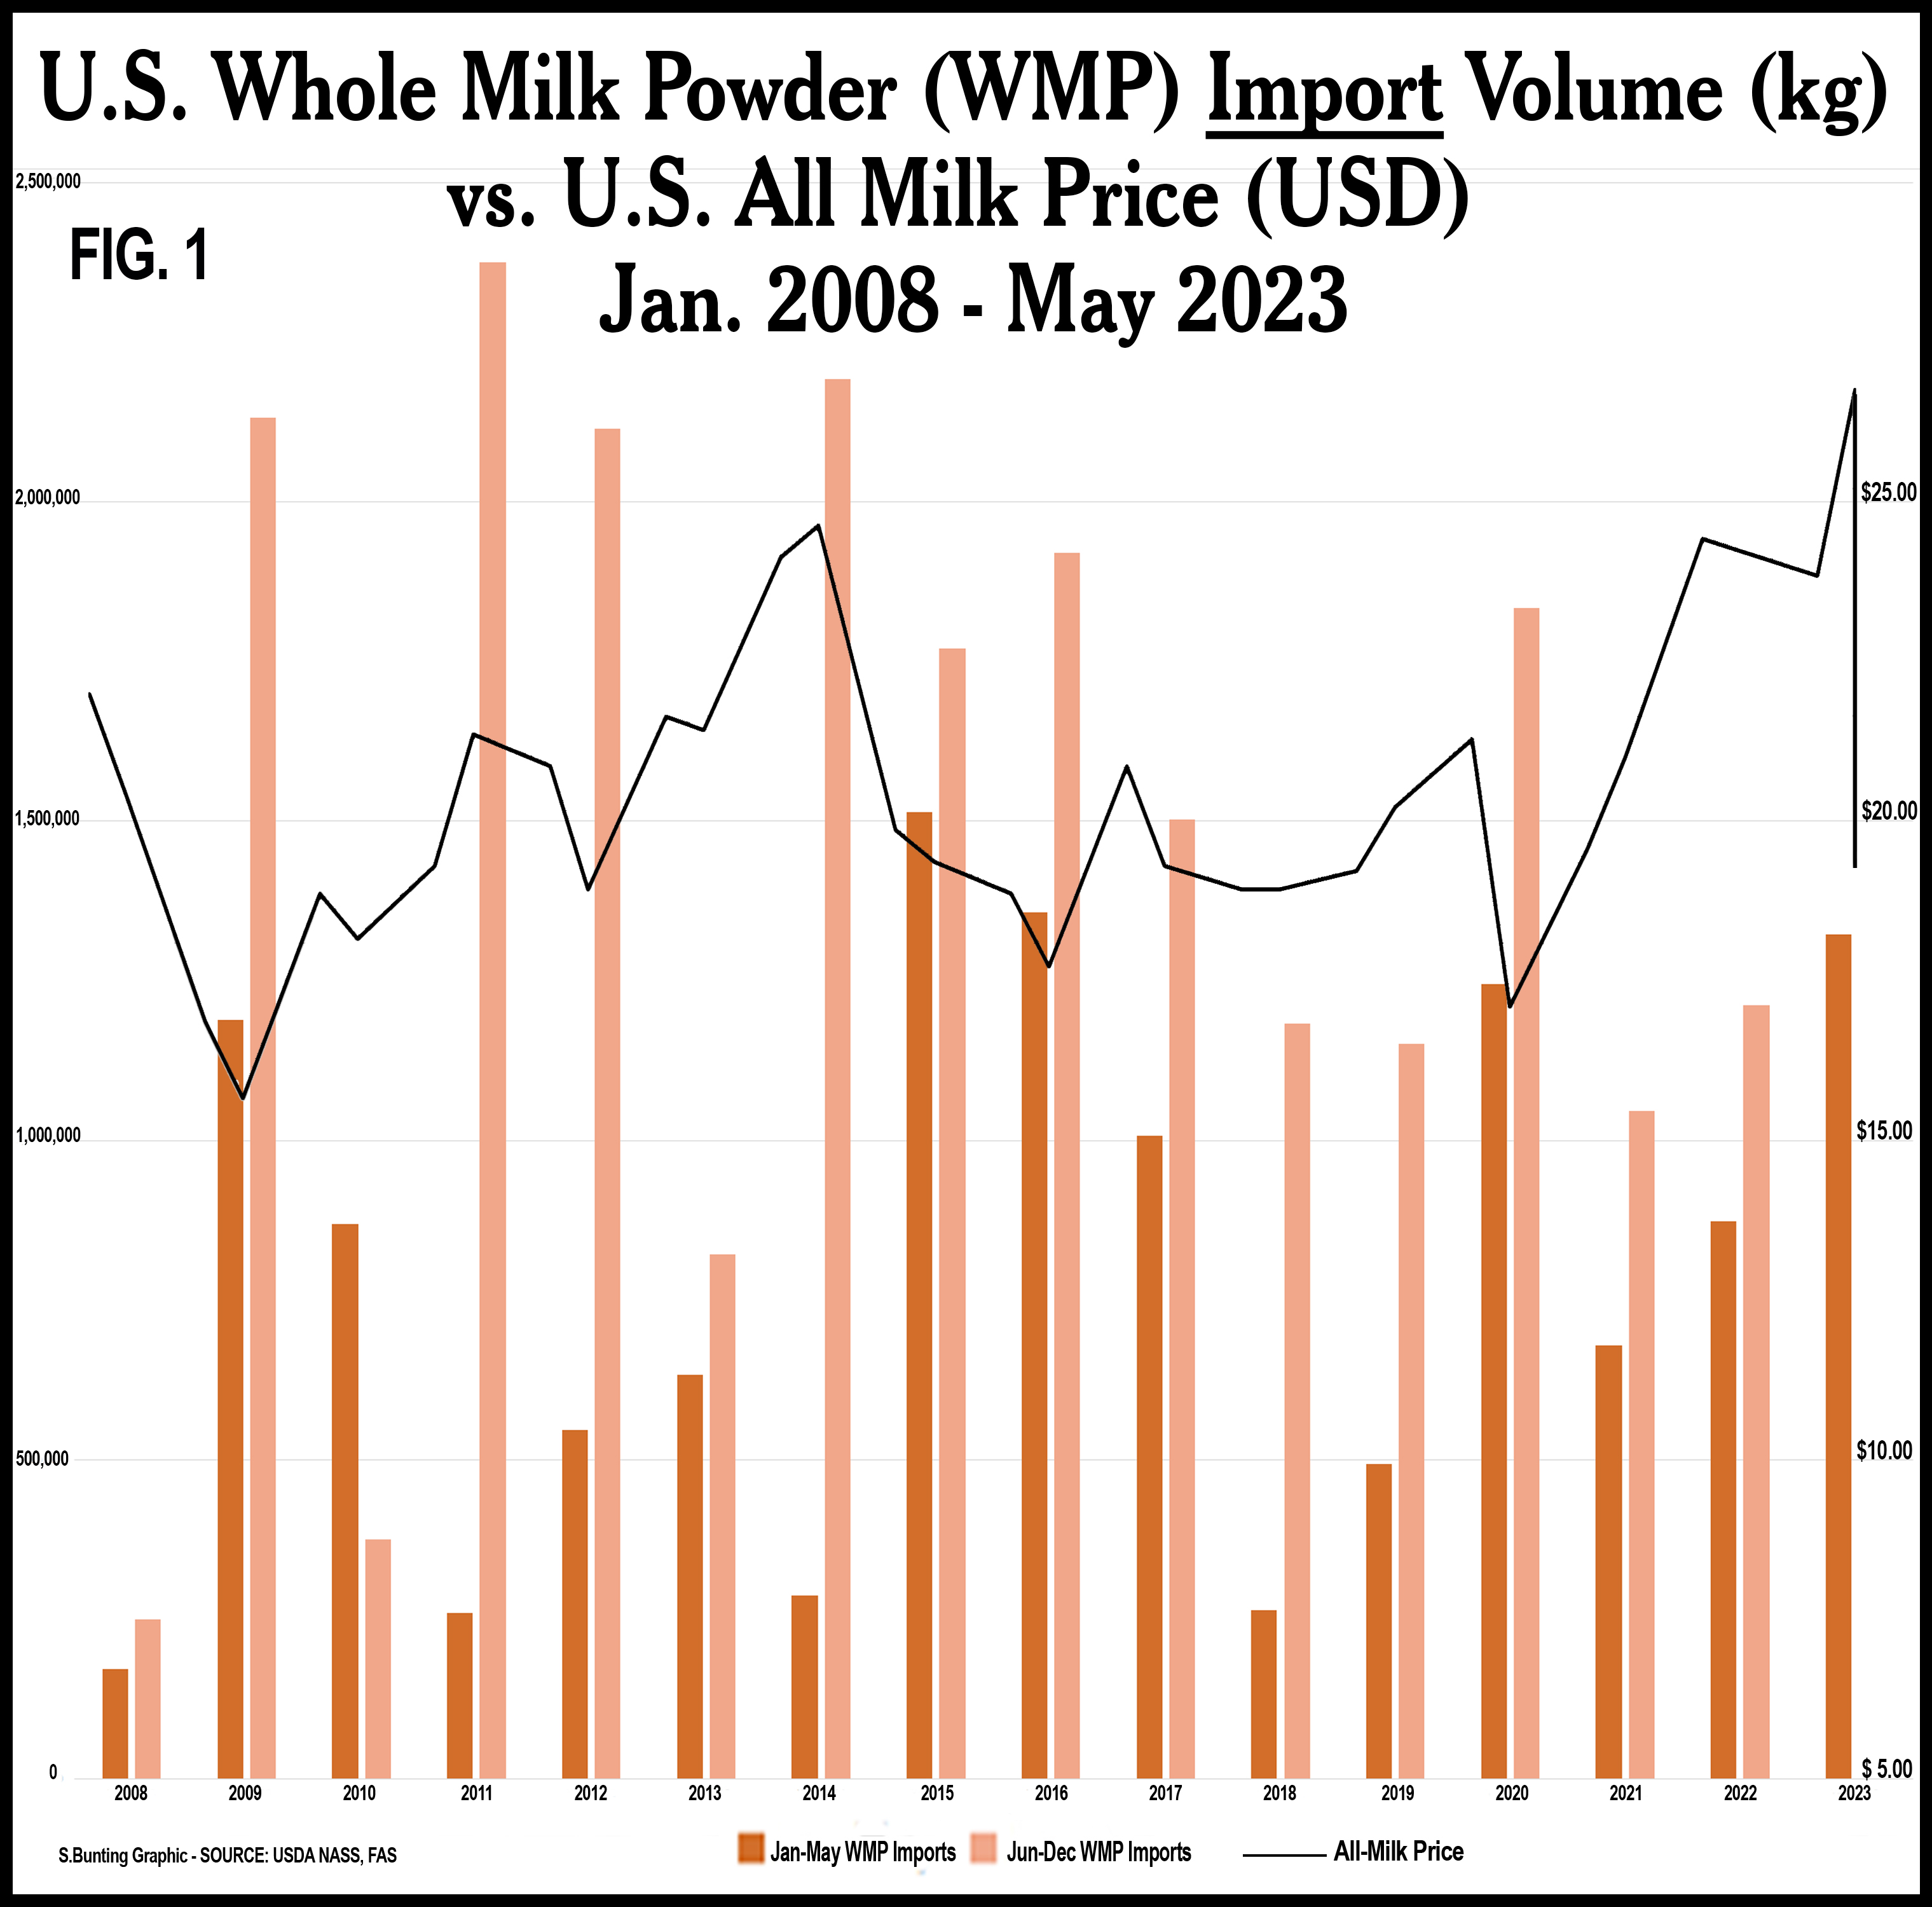
Of course, no one (but Farmshine) mentioned the rising imports that were reported in Part One of this series.

Looking for context on the imports, we reached out to retired cooperative executive Calvin Covington, who follows these things on a total solids basis and has been watching the whey market as a leading milk market indicator. We learned that his calculations on a total solids basis, pegged January through April 2023 imports of dairy products into the U.S. at levels 15% higher than a year ago!

“The 15% equals 39.3 million lbs. more solids,” Covington wrote in an email response to a Farmshine question. “Most of the imports are coming from Europe. Dairy demand is very weak in Europe, consumers have less money to spend. Those milk solids are moving out of Europe.”

Noted Covington in June: “On a total solids basis, ending dairy stocks as of April 30th are 3% higher than last April. The 3% equals 61.5 million lbs. more solids.”

This means the 15% increase in January through April dairy product imports — on a total solids basis — were equal to more than half (63%) of the 3% increase that was reported in April domestic ending stocks of all dairy product inventories on a total solids basis.

Think about that for a minute. Product came in and was inventoried while domestic milk was dumped, and producer prices were crushed so that the domestic price could fall below the global price so then the U.S. dairy exports could increase? It makes the head spin.

Class I sales were down during this time, especially in the Midwest where some fluid plants have closed. Fresh Italian cheese production was down, and that’s a big one for Wisconsin. Together these factors pushed more milk to make more American cheese at that time, some of it delivered to consumers in smaller packages (rationing). 

A wrinkle in the market-fabric comes from the dairy foods complex importing higher volumes, and there are the fake bioengineered microorganisms from which excrement is harvested and described as ‘dairy casein or whey protein without the cow.’ These analogs are being heavily marketed to large food manufacturers making dairy and bakery products as carbon-footprint-lowering dairy protein ‘extenders.’

So much so, that National Milk Producers Federation recently sent a letter to FDA asking the agency not to make the same mistake with these fake products as has been made with plant-based frauds.

However, as we look at the modest milk production increase for the first half of 2023, overall, and compare it to 2022, the total comparison was flattish then and it is declining now as we move toward Q3.

But there’s another major twist to this supply-demand equation:

The location and purpose of dairy expansion is undergoing accelerated transformation on a geographic and structural basis. This transformation is part of the “U.S. Dairy transformation” that the national dairy checkoff has promoted in its Pathways to Net Zero Initiative… and it is affecting the milk pricing for all U.S. dairy farmers, everywhere.

Here’s the problem: Milk production in the Central U.S. has expanded by much more than the national average. 

Even University of Wisconsin economics professor emeritus Bob Cropp noted in his writing after the May report that growth in the Midwest — where cheese rules the milk check — was outpacing processing capacity, and the existing capacity to process all this milk was being reduced by labor and transportation challenges.

The concentrated expansion of milk production in the Central U.S. has been accelerating since 2018, but a new paradigm is now in effect: New concrete is being poured in the targeted growth areas driven more by manure, than by milk, and new dairy processing plant construction that is completed and in the works is targeting the same areas.

This is creating a production bubble that is a flood within calmer seas.

Some are calling it the California RNG gold-rush as developers construct Renewable Natural Gas (RNG) projects — especially on new large dairies — for the California RNG market and to collect the low-carbon-fuel credits for the California exchange and other exchanges that are and will be emerging, thanks to the USDA Climate Smart wheel-of-fortune.

We’ve heard the national dairy checkoff managers from DMI talk about profitable sustainability, markets for manure, promotion of other revenue streams for dairy farms as part of the mantra the checkoff has assumed for itself as speaker for all-things-dairy for all-dairy-farmers on what is “sustainable” for the industry.

When the Net-Zero Initiative was launched — along with DMI’s industry transformation plan — it was something that had been in the works since 2008 and emerged more prominently in the 2017-21 period when the former and current U.S. Ag Secretary Tom Vilsack did his stint as top-paid DMI executive, presiding over the U.S. Dairy Export Center (USDEC) under DMI’s umbrella and as a top-talker on the Innovation Center for U.S. Dairy, also under DMI’s umbrella. 

All three: DMI, USDEC, and Innovation Center for U.S. Dairy are 501c6 non-profit organizations contracted to spend checkoff dollars. A 501c6 is essentially a non-profit that can lobby policymakers, whereas the 501c3 National Dairy Board cannot.

In 2020 and 2021, the Innovation Center — filing tax returns under the name Dairy Center for Strategic Innovation and Collaboration Inc. — doubled its revenue from around $100 to $150 million annually to $300 to $350 million.

We all heard it, read it, thought about it – maybe – that the checkoff was morphing into a facilitator for the transformation of the dairy industry led by manure-promotion, not necessarily milk promotion, with the mantra of feeding the world, being top-dog internationally, and meeting international climate targets with a Net Zero greenhouse gas pledge. (That pledge and the methane calculation are another story Farmshine readers are aware of, but we’ll leave that big driver off the table for this discussion.)

Here we are, now seeing an industry being created from within the broader dairy industry with new production driven by manure, in regions where new or expanding cheese, whey and ingredient plants are being located and potentially displacing production from plants and farms elsewhere that are not tied-into this manure-to-methane wheel-of-fortune using dubious science and math to overpeg a cow’s global warming impact.

While that production bubble is building in targeted growth regions with cheese-heavy milk checks, driven in part by manure-focused expansion, it bursted at the seams this summer due to a processing capacity bottleneck, compounded by supply chain disruptions and a sudden decrease in the production of fresh cheese at other plants and a sudden 18% decline in the amount of milk processed for Class I fluid use in the Upper Midwest.

Here’s the sticky wicket. A review of the 2022 end-of-year milk production report along with reports issued in the first half of 2023, revealed that, indeed, the Central U.S. was “awash in milk.” 

Zooming in on the milk production reports, we see South Dakota continuing its fast and uninterrupted growth — up 15.5% for 2022 vs. 2021, and up 7.4% Jan-May 2023 vs. 2022 — having leapfrogged Vermont, Oregon and Kansas and closing in on Indiana in the state rankings. 

Neighboring Iowa leapfrogged Ohio in 2022 with a 4.7% gain in milk production Jan-May 2023 vs. 2022. Number 7 Minnesota grew again after taking a breather with a 0.6% decline in 2022, then increasing 2% in production Jan-May 2023. 

The tristate I-29 corridor, where cheese processing capacity has been expanding, was up 3.3% in milk production collectively with 19,000 more cows Jan-May 2023. Add to this the 1.3% increase in number 2 Wisconsin’s May milk production, and we saw the quad-state’s collective increase was 203 million pounds of additional milk in the region vs. year ago in May, although Wisconsin’s contribution came from 3000 fewer cows, according to USDA.

Just west in number 3 Idaho, production jumped 3.1% with 7,000 more cows Jan-May 2023.

To the east in the Michigan-Indiana-Ohio tri-state region — where the large new cheese plant in St. John’s, Michigan is fully operational — collective milk output was up 2% over year ago with 11,000 more cows. In 2022, this tri-state region was down 2 to 3% for the year compared with 2021.

Number 5 New York made 2.1% more milk with 7,000 more cows in May vs. year ago, with most of this expansion in the western lake region. 

Number 1 California shrank milk production by 0.7% in May with 2000 fewer cows, and number 4 Texas flattened out its multi-year accelerated growth curve to make just 0.8% more milk in May than a year ago with just 1000 more cows, largely affected by the devastating Texas barn April fire resulting in the loss of around 20,000 cows. 

Neighboring New Mexico continued its multi-year downward slide, ranked number 9 behind a flat-to-slightly-lower milk output in number 8, Pennsylvania. 

Milk production in New Mexico fell 3.8% in May vs. year ago with 10,000 fewer cows. This followed an 8.4% decline in milk production and a 30,000-head cut in cow numbers for the year in 2022. Producers there cite well-access limitations, severe drought, high feed costs with reduced feed availability, as well as receiving the rock-bottom milk price as the reasons dairies in New Mexico are closing or relocating. 

With all of these factors in play, the production reports show a clear paradigm shift in how the dairy industry expands via transformation. It is being driven to where feed is available and milk output per cow is higher, and it’s now being driven by a non-milk-related factor: MANURE for the RNG ‘goldrush’

A saving grace is cattle are in short supply, with replacements bringing high prices. This fact is slowing the bubble, production is declining now, and prices are recovering from those unanticipated lows.

-30-

Fluid milk processors say they can’t recoup higher protein value

NMPF, NAJ say higher solids worth more nutritionally, Seek FMMO updates to avoid misalignments and disorderly marketing

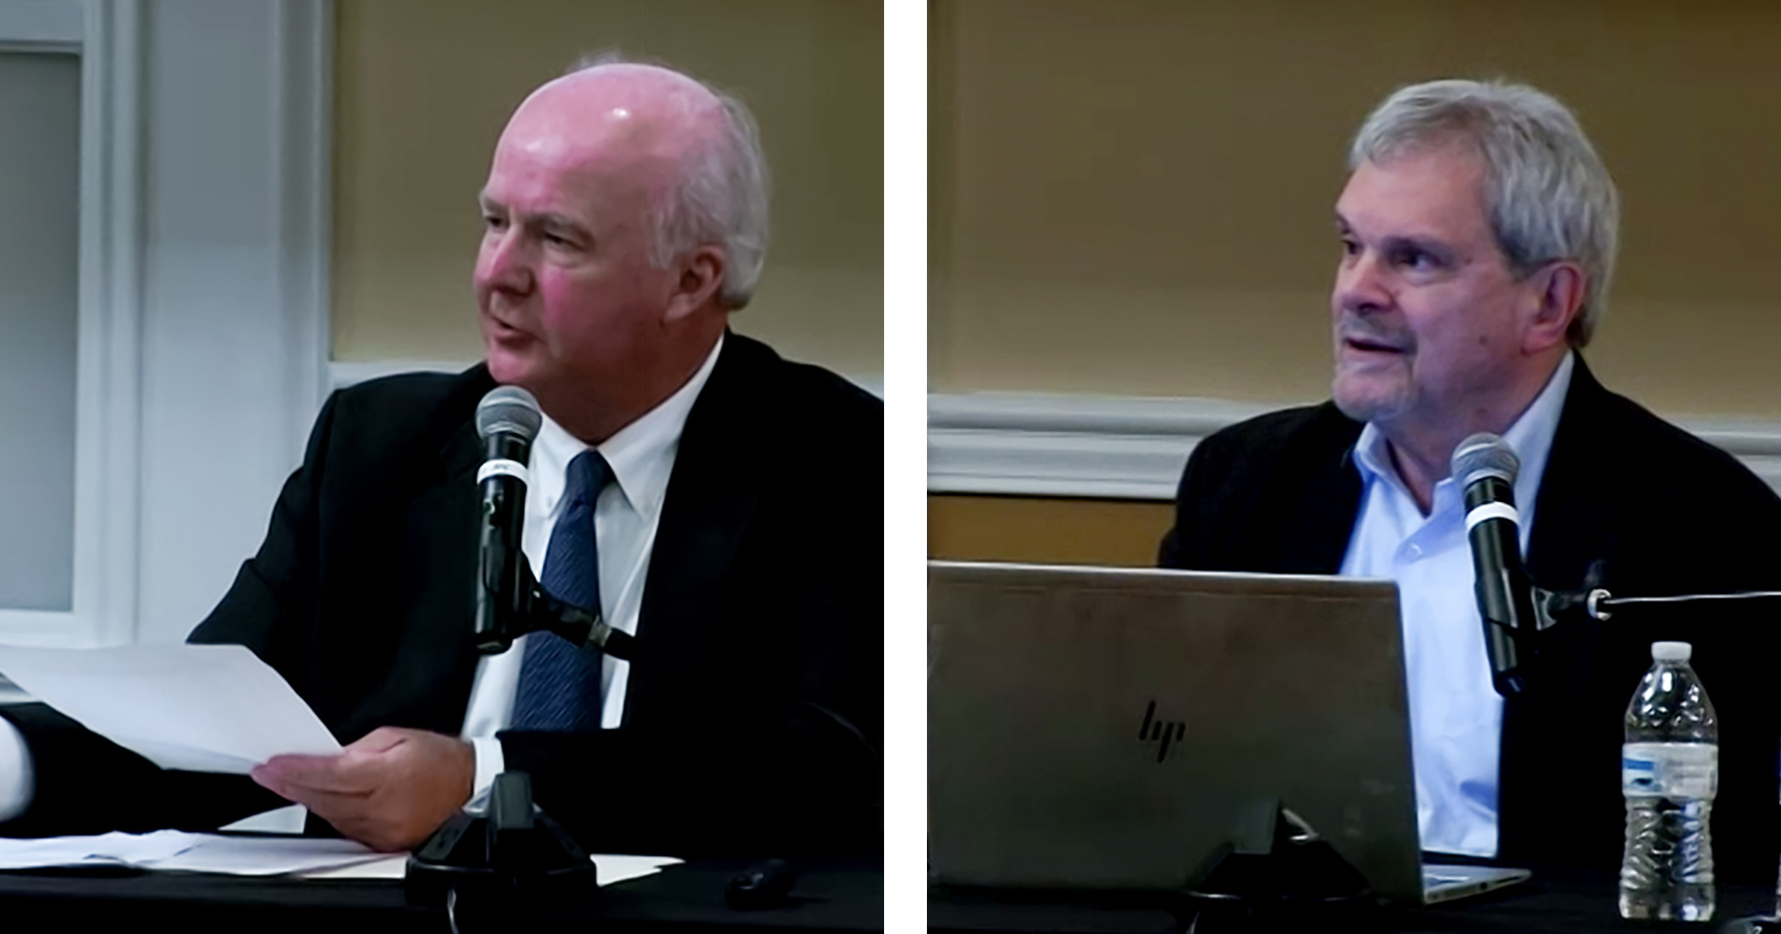
Calvin Covington (left) for Southeast Milk and Peter Vitaliano for National Milk Producers Federation testified on what the outdated skim milk component standards mean in terms of underpaying farmers and eroding producer price differentials (PPD), leading to disorderly marketing. This occurs because the skim portion of the milk that is utilized in manufactured products (Class III and IV) is paid per pound of actual protein, solids nonfat and other solids; whereas the skim portion of the milk bottled for fluid use (Class I) is paid on a per hundredweight basis using the outdated standard skim solids levels. The fat portion is not an issue because it is already paid per pound in milk class uses. Screen captures, hearing livestream

By Sherry Bunting, Farmshine, Sept. 8, 2023

CARMEL, Ind. – The national Federal Milk Marketing Order hearing completed two weeks of proceedings, so far, in Carmel, Indiana. The entire hearing is expected to last six to eight weeks, covering 21 proposals in five categories.

Picking up the livestream online, when possible, gives valuable insight into a changing dairy industry and how federal pricing proposals could update key pricing factors.

The first week dug into several proposals to update standard skim milk components to reflect today’s national averages in the skim portion of the Class I price. 

Here is a bite-sized piece of that multi-day tackle.

National Milk Producers Federation (NMPF) put forward several witnesses to show what the outdated component levels mean in terms of underpaying farmers, and how paying for the skim portion based on outdated component levels has eroded producer price differentials (PPD), leading to disorderly marketing.

IDFA’s attorney Steven Rosenbaum grilled NMPF economist Peter Vitaliano on this. He tried on seven attempts to establish that the fat/skim orders in the Southeast don’t have component levels as high as the national average, suggesting this change would “overpay” producers in some markets.

In his questioning, Rosenbaum stressed that fluid milk processors can’t recoup the updated skim component values if those components do not “fill more jugs.”

Vitaliano responded to say that protein beverages are a big deal to consumers, and some milk marketing is being done on a protein basis. Rosenbaum asked for a study showing how many fluid processors are actually doing this.

Attorneys for opposing parties kept going back to this theme that the skim solids should not be updated because the FMMOs are based on “minimum” pricing. They contend that processors can pay “premiums” for the extra value if they have a way of recouping the extra value by making more product or marketing what they make as more valuable.

Vitaliano disagreed, saying that even though many processors do not choose to market protein on the fluid milk label, “more protein makes fluid milk more valuable to consumers.”

Attorney Chip English went so far as to ask Calvin Covington on the stand: Why should my clients (Milk Innovation Group) have to pay more for the additional solids in the milk when they are removing some of those solids by removing the lactose?

“Consumers don’t want lactose,” English declared.

Covington, representing Southeast Milk and NMPF, responded to say: “I don’t know that to be true. It is unfair to suggest all.”

Bottomline, said Covington, raising standard skim solids to reflect the composition of milk today vs. 25 years ago adds money to the pool to assist with the PPD erosion so that Federal Orders can function as they were intended and so producers are paid for the value.

As English further questioned whether consumers even care about the higher skim solids and protein levels of milk today, Covington replied: “Skim milk solids have a value in Class I, or fluid milk. People don’t buy milk for colored water. The solids give it the nutritional value. That’s the reason they buy milk. That’s why FDA set minimum standards in some states. Why would you drink milk if not for the nutritional value?”

He also pointed out that the increase in solids nonfat over the past 20-plus years has improved the consistency of lower fat milk options. As noted previously, the milkfat is a separate discussion and is not included in this proposal because farmers are already paid per pound for their actual production of butterfat in all classes, including Class I.

Under cross examination, Covington explained that the Class I price in all Federal Orders pays for skim on a standardized per hundredweight basis and pays for fat on actual per pound basis. Meanwhile, the manufacturing classes pay for both skim and fat on a per pound of actual components basis. 

As skim component levels have risen in the milk, the alignment of Class I to the manufacturing classes narrows because of the differences in how the skim is paid for. When this happens, it becomes more difficult to attract milk to Class I markets. That’s one example of disorderly marketing. PPD erosion and depooling of more valuable manufacturing class milk is another example. 

Covington explained the impact of this misalignment on moving milk from surplus markets to deficit Class I markets, that the lower skim value becomes a disincentive.

Vitaliano explained the depooling issue as “creating disorderly marketing conditions also, and great unhappiness when one farm is paid a certain price and another handler pays a different price (in the same marketing area). That’s disorderly unhappiness for the Federal Order program,” he said.

He noted that the fundamental reason for pooling is to take the uses in a given area with different values to achieve marketwide pooling where producers in that Federal Milk Marketing Area are paid similarly, regardless of what class of product their milk goes into.

“This removes the incentive for any one group to undercut the marketwide price to get that higher price (for themselves),” he said. “The Orders create orderly marketing with a uniform price. Depooling undermines that fundamental purpose that is designed to create orderly marketing.”

Either way, whether indirectly paying to bring supplemental milk into Class I markets from markets with higher manufacturing use, or in the case of depooling, the dairy farmers end up paying for the fallout from this erosion of the PPD.

Since the beginning, even before 2000 Order Reform, figuring the Class I base milk price had to begin somewhere, according to Covington. Federal pricing has always used the manufacturing class values in determining that base fluid milk price.

The trouble today is that Class III and IV handlers pay farmers per pound of actual skim components in the milk they receive, while the Class I handlers pay per hundredweight based on an arbitrary outdated national average skim component standard. Thus, the “opportunity cost” of moving this now higher component milk to manufacturing classes that pay by the actual pound of protein, for example, instead of by the old standard average protein levels is not accounted for in the Class I price that still uses the old standard average levels.

Pressed again on how it makes sense to raise Class I prices by raising the component level of the skim to more adequately reflect the national average today, Covington said: “It adds to the nutrition, and I stand by that. In proposal one, the price will go up (estimated 63 cents per cwt or a nickel per gallon). I am comfortable charging that extra price to Class I processors.”

Attorney English, representing MIG, retorted that, “The handlers who buy milk and then by adding a neutralizing agent remove the lactose, they’re going to pay more for the milk that they then have to process to subtract the lactose.”

Covington responded that, “There are consumers who think about lactose. There are consumers who buy lactose-free products, yes, because it is on the shelf, but it’s not all consumers.”

On the higher protein, English asked Covington how Class I processors are supposed to monetize that protein in a label-less commodity, a commodity that is declining in its share of total milk utilization?

“We are still selling 45 billion pounds of packaged fluid milk (annually) in this country,” said Covington. “Consumers wouldn’t buy that 45 billion pounds if it wouldn’t have some nutrition.”

English argued that milk is sold as whole, 2%, 1% and non-fat. It is not sold by its protein, so isn’t it “so highly regulated in ways that alternatives are not that any increase in price hinders sales of fluid milk?”

Covington acknowledged that, “yes, it is regulated, but I’m not convinced that this proposal will hinder fluid milk sales. Again, (higher components) add to the nutrition and I stand by that.”

Opponents kept coming back to these value questions, while proponents focused on the price alignment issue and orderly marketing.

To link up with the hearing livestream 8 to 5 weekdays, to read testimony and exhibits, and to respond to the virtual farmer testimony invitations made every Monday for the following Friday, visit the Hearing Website at https://www.ams.usda.gov/rules-regulations/moa/dairy/hearings/national-fmmo-pricing-hearing

-30-

Rocky start for National FMMO hearing amid calls for broader scope, intense cross-examination on data, exhibits

By Sherry Bunting, Farmshine, August 23, 2023

CARMEL, Ind. — USDA’s much anticipated national public hearing of 21 proposals on amendments to uniform pricing formulas for all 11 Federal Milk Marketing Orders (FMMO) had a rocky start on Wednesday, Aug. 23 in Carmel, Indiana. The first day kicked off amid objections  to the hearing scope as fluid milk processors were seeking to get their excluded Class I proposals onto the docket.

The presiding administrative law judge set the stage for what he said will be an estimated 7-week hearing, held 8 to 5 ET every weekday with virtual farmer testimony on Fridays. (It is being livestreamed for watching by zoom or listening by phone. Look for that information in the graphic above, or find the links and numbers at the end of this article or at the hearing webpage).

The judge stated his authority to interrupt for comments or testimony outside of the hearing scope. “I will not issue a decision,” he said. “USDA will take the information to render a decision.”

Once a recommended decision is put forward by USDA, expected in February or March 2024, a comment period follows before the final decision is issued in June or July and made fully effective in the fall of 2024. Some proposals call for a 12-month delay in implementation, so the full effect of potential decisions could be delayed until fall of 2025.

Given the rocky start to the hearing, even this timetable could be prolonged, but USDA is under a Congressional mandate to render decisions within 18 months of a petition it agrees to hear.

Immediately following the setting of the stage, Chip English, attorney for the Milk Innovation Group (MIG) put forward an objection and a motion seeking reversal of USDA’s decision that excluded two of its Class I pricing proposals from the hearing announcement. One of the excluded proposals would exempt organic milk from FMMO pools and the other deals with ‘shrink’ in the extended shelf life category.

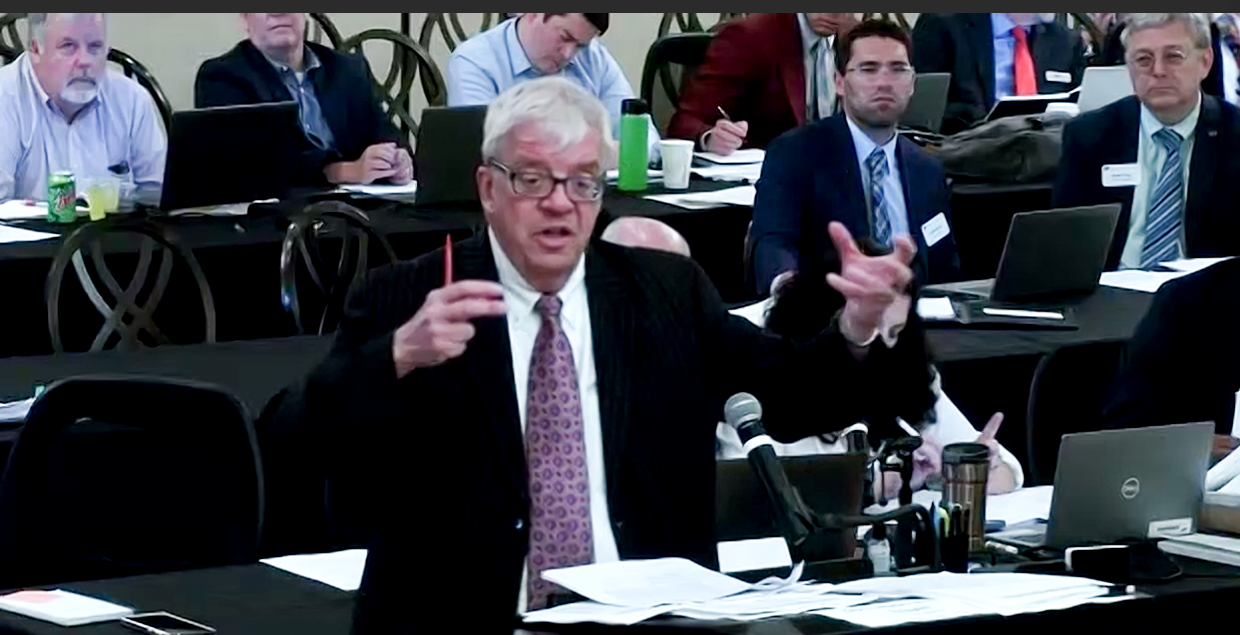
Attorney Chip English for the Milk Innovation Group (MIG) kicks off federal milk pricing hearing with objections to scope, saying two of their Class I pricing proposals were improperly excluded. Screen capture from livestream of first day of 7-week national public hearing on federal milk pricing formulas

“It’s all coming in whether you like it or not,” said English, “because at the end of the hearing, we’re going to be talking about raising Class I, and these are issues that have to be part of that.”

Attorney John Vetne for National All Jersey joined in the objection on procedural grounds because NAJ also had its proposal to make all 11 FMMOs use multiple component pricing was rejected from the hearing. Currently, the 3 southern marketing areas and Arizona are fat/skim priced, whereas the other 7 marketing areas use multiple component pricing (MCP). USDA excluded this proposal since the 4 fat/skim priced marketing areas must regionally call for the change to MCP pricing.

Within the first hour and a half of the first day, the hearing went “off record” into private discussion about handling the objections and handling the exhibits.

In addition to the hearing scope objections, there was extensive cross-examination of USDA AMS Dairy Program staff on its fulfillment of data requests and various exhibits provided by USDA — in some cases calling into question the comparability or reliability of some of the data.

For example, much was made of the differences between the USDA mailbox milk price report as compared to the Federal Order price announcement. Mr. English probed USDA staff on how these reports are audited, how the data is collected, what is included and what it is based on. He did what he has done in Pennsylvania Milk Marketing Board (PMMB) hearings in the past to discredit the comparability of the mailbox price report to state or federal “announced price” reports — because of the differences in the “auditing”.

As each exhibit on pooling figures and other data was put under the cross-examination microscope, the issue of “restricted” data came up due to “confidentiality,” which USDA staff explained is necessary when 2 or fewer companies are in a marketing area — be they plants or farms. In the rapidly consolidating dairy industry, what does this foretell of future market transparency if data are not available for price discovery and market transparency because of too few operators in a region?     

There were attempts to keep some exhibits from being included in the hearing record. Most of these discussions were put on hold to be explored through further cross-examination at a later time with future witnesses.

In many ways the sense of this round of cross-examination on exhibits felt a bit like cutting the legs out from under future presentation of proposal testimony even before they get to the floor. Basically, much legal maneuvering on data before the first proposal is even heard and testified to.

If the first day is any indication of what is in store, expect to see many attempts to push the scope boundaries, and expect the judge to err on the side of making sure USDA has all of the information it needs to render decisions, so some latitude will likely be given for these boundary explorations by attorneys.

Attorney English, is well known to any Pennsylvania dairy farmer who has ever sat in on a PMMB hearing in Harrisburg. He has represented Dean Foods and the Pennsylvania Milk Dealers in past years on the price-setting hearings conducted by the PMMB. In fact, the esteemed milk accountants of Herbein and Co. in Pennsylvania are providing material for some of the MIG opposition arguments to come. Cheap Class I milk is the name of the current game.

The MIG will be working overtime through Mr. English to make sure Class I prices are not raised, and in fact are lowered at the farm level since one of their proposals that WAS accepted by USDA is to remove the base Class I price differential of $1.60/cwt from every FMMO — across the board.

Who is the MIG? The Milk Innovation Group members include Anderson Erickson Dairy Co., Inc.; Aurora Organic Dairy; Crystal Creamery; Danone North America; Fairlife; HP Hood LLC; Organic Valley/CROPP Cooperative; Shamrock Foods Company; Shehadey Family Foods, LLC (Producers Dairy Foods, Inc.; Model Dairy, LLC; Umpqua Dairy Products Co.); and Turner Dairy Farms.

After lunch, some high points of the first day included Dr. Roger Cryan for American Farm Bureau Federation requesting volume data on all of the salted and unsalted butter that is graded by USDA AMS for retail. This, he said, is four numbers and should be readily available. It is germane to AFBF’s proposal to include unsalted butter in the product price survey used in the Class IV pricing formula.

Testimony began late in the afternoon on the first proposal from NMPF to raise component levels in the uniform pricing formulas to more accurately reflect today’s protein and other solids levels.

Peter Vitaliano, NMPF’s vice president for economic policy and market research, laid out the proposal and was subjected to intense cross-examination with the promise of hours more of cross examination on the second day by Mr. English before even getting to the first expert fact witness — Calvin Covington, for Southeast Milk and NMPF.

While NMPF witnesses will show the outdated component levels are giving a ‘deal’ to Class I processors paying less for skim that is more valuable today in terms of components, IDFA’s attorney Steven Rosenbaum grilled Vitaliano on this. He tried on seven attempts to establish that the fat/skim orders in the Southeast don’t have component levels as high as the national average by asking for this breakout in seven differently-phrased questions, all the while discreetly suggesting that this change would “overpay” producers in fat/skim orders.

He also questioned how fluid milk processors are supposed to recoup that value if it doesn’t “fill more jugs of milk”. Vitaliano responded to say that protein beverages are a big deal to consumers, and some milk marketing is being done on a protein basis. Rosenbaum asked for a study showing how many fluid processors are doing that, and then basically said, in lawyer speak, the equivalent of ‘never mind,’ as Vitaliano interjected that it’s more valuable to consumers.

In this reporter’s mind, the thought that kept popping up during that exchange was this: If IDFA and MIG are so intent on suppressing the Class I price to avoid paying for the improved value of milk, then maybe they should then start forking over their cost data in audited surveys to the USDA to justify the $3.60 per hundredweight they are getting subtracted from the base Class I price in the form of Class III and IV make allowances that do not even apply to them, but they get that deal anyway.

These are just a few thoughts from an intense first day of the national FMMO hearing that NMPF is calling the “first in a generation opportunity” to make key adjustments to the milk pricing formulas to reflect a changing dairy industry. It appears that many of their proposals will help farmers… We’ll see over the next 6 to 8 weeks where it’s all going.

In the meantime, Congress may want to think about fixing the Class I mistake it made in the 2018 farm bill by changing four simple words from ‘average plus 74 cents’ to ‘higher of’ and at least get that done timely.

This hearing could leave that objective in the dust if the first day is an indication of what is to come.

Information to tune in by livestream through zoom or to dial-in and listen from a cell phone or landline has just been announced.

View the hearing at this link: https://www.zoomgov.com/j/1604805748  and enter Webinar ID 160 480 5748

Or listen via one tap mobile: +1.646.828.7666, using ID 1604805748#

Or listen via landline telephone: +1.669.254.5252 and enter ID 160 480 5748

The hearing schedule will proceed in this order to consider accepted proposals under these categories, according to USDA:

1. Milk Composition (component yield) proposals.

2. Surveyed Commodity Prices (removing or adding commodities to the weekly price surveys used in the class and component pricing formulas).

3. Class III and IV Formula Factors, which includes various ‘make allowance’ proposals as well as butterfat recovery factors, and farm-to-plant shrink.

4. The Base Class I Skim Price (Mover) Formula (6 proposals, 3 favoring return to ‘higher of’, including 2 that also favor eliminating ‘advanced pricing’ of Class I. )

5. Class I and II Differentials.

Copies of the notice, a list of proposals being considered, guidelines for how to participate, the hearing schedule, and corresponding hearing record can be found and followed on the Hearing Website at https://www.ams.usda.gov/rules-regulations/moa/dairy/hearings/national-fmmo-pricing-hearing

For technical difficulties, please email FMMOHearing@usda.gov

-30-

USDA will hear 21 milk pricing proposals beginning Aug. 23; Front-and-center: May 2019 change in Class I (without a hearing) costing farmers $1 bil. over 52 mos.

By Sherry Bunting, Farmshine

WASHINGTON –- USDA officially announced Monday (July 24) the national public hearing to consider proposals seeking to amend the uniform pricing formulas across all 11 Federal Milk Marketing Orders (FMMO). The hearing begins Wednesday, August 23, 2023 at 9:00 a.m. at the 502 East Event Centre, 502 East Carmel Drive, Carmel, Indiana.

Farmers will be able to testify in person at any time, or virtually on Fridays by pre-registering.

Approximately 40 proposals were submitted by 12 organizations and were explained during a webinar in mid-June. Of those, 21 will be considered within the uniform pricing scope of the hearing, according to the USDA notice. Copies of the notice, a list of proposals being considered, guidelines for how to participate, the hearing schedule, and corresponding hearing record can be found and followed on the Hearing Website.

The Class I mover formula will be addressed in the national hearing’s scope, including the proposals from National Milk Producers Federation and American Farm Bureau to go back to the ‘higher of’ method. The change from ‘higher of’ to ‘average of’ was made legislatively in the 2018 farm bill without a hearing.

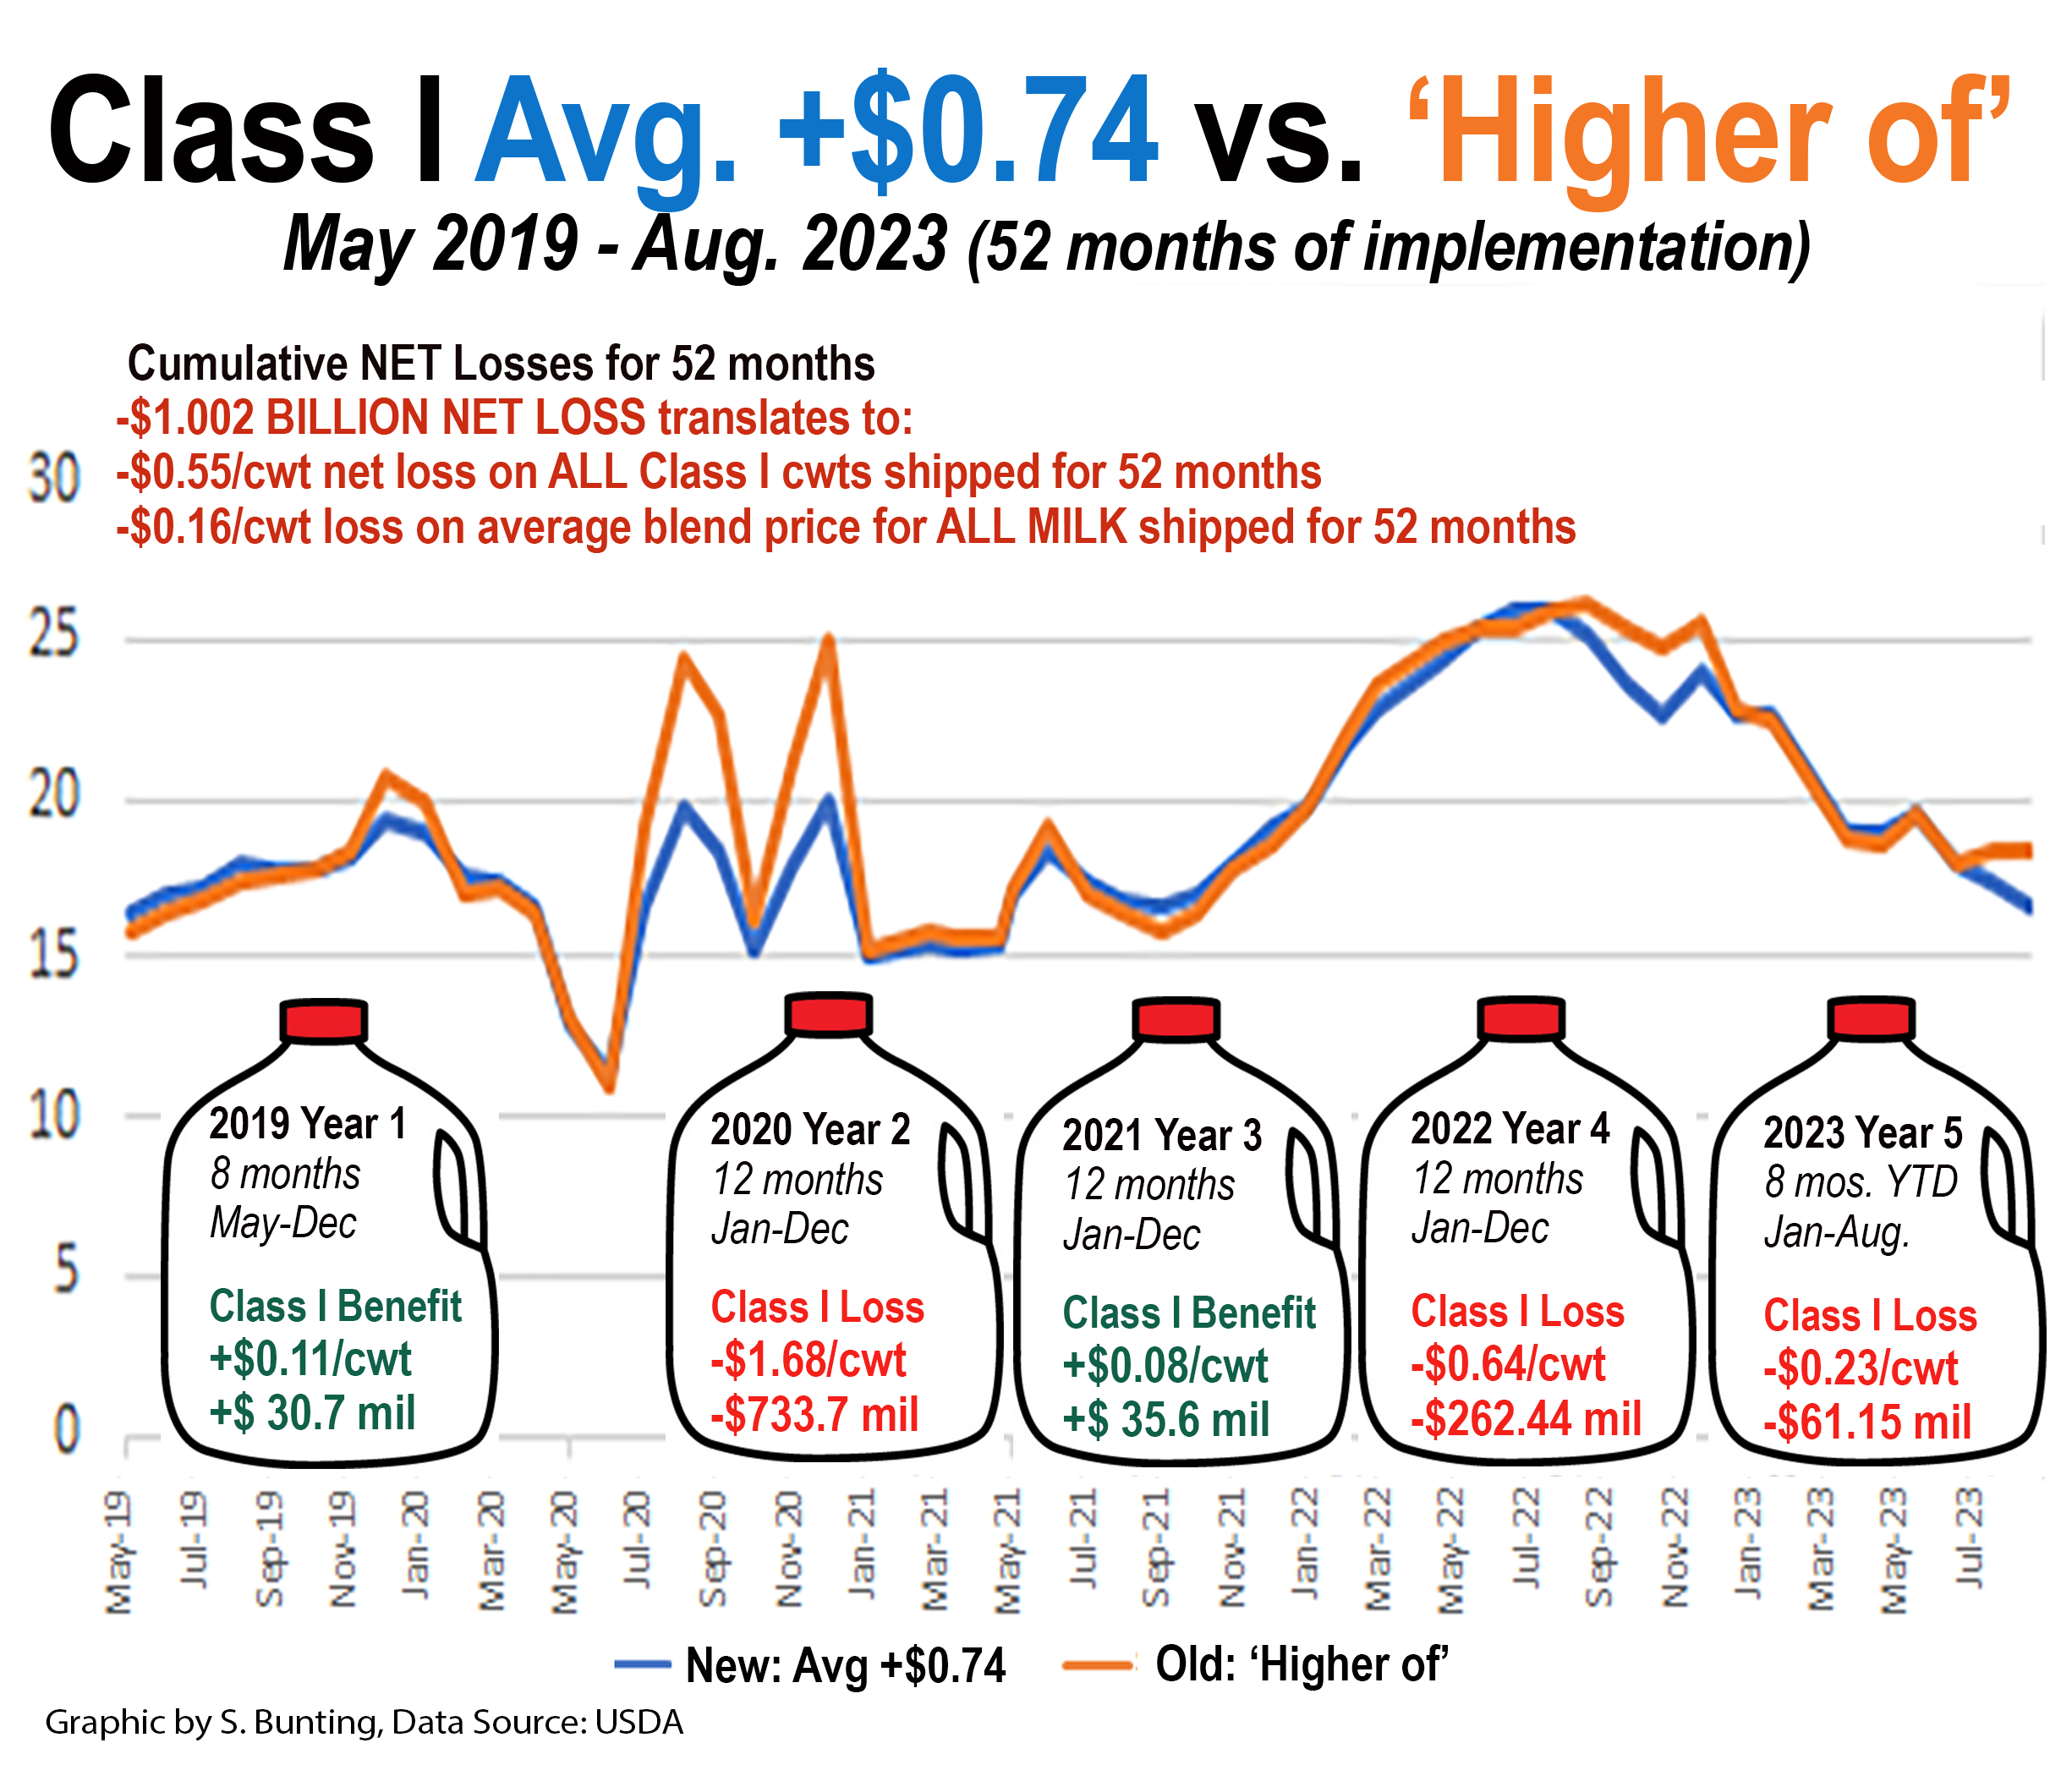
Since USDA implemented the ‘average of’ method in May 2019, net losses from this change are projected to exceed $1 billion after August 2023 milk is paid for in September.

On July 19, USDA announced the August advance Class I price mover at $16.62. If the previous ‘higher of’ method had been used, the Class I base price would have been $18.29. That’s a $1.67 per hundredweight loss on all Class I milk next month. July’s Class I mover was also calculated substantially lower (by $1.02) using the ‘average of’ vs. the ‘higher of.’ These losses will impact August and September milk checks for July and August milk.

Around 28% of all milk produced in the U.S. is Class I fluid use, so farmers stand to lose an additional 47 cents per hundredweight on all of the milk they market in August and 29 cents on all the milk they market in July — just from this formula change. This is on top of the market declines in the class and component prices. The loss to blended prices will be greater in some Federal Orders and less in others, and this does not include the impacts from de-pooling of higher-value Class IV milk.

The impact of the two-week Class I advance pricing factors is compounded by the ‘average of’ method, which is quite notable for July and August. Cheese and whey were in a tailspin lower; however, on the very next day after the August Class I base price mover had been averaged and locked-in on July 1-15 pricing factors, the dairy product markets began a huge rally, with cheese gaining nearly 40 cents in 8 trading sessions. This boosts the other class and component values much higher for the latter half of the month.

Over the 52 months of its implementation, the ‘average of’ formula has effectively removed an estimated 55 cents per hundredweight from farmer payment for all Class I milk, according to USDA data. On a blended uniform price, this comes out to a national average loss of 16-cents on every hundredweight of all milk used in all classes of products shipped from May 2019 through August 2023. That is like paying another checkoff for 52 months.

Among the other proposals included in the national hearing is the American Farm Bureau (AFBF) Class I and II proposal that seeks return to the ‘higher of’ with additional adjustments such as eliminating the two-week ‘advanced’ pricing.

IDFA’s Class I proposal seeks to keep the ‘average of’ and use either the current 74-cent-adjuster or a ‘rolling adjuster’ based on a calculated difference over 24 months, whichever is higher.

Milk Innovation Group’s (MIG) proposal seeks to keep the ‘average of’ but change the ‘adjuster’ monthly via a 24-month look-back with a 12-month lag.

Two Edge Cooperative proposals are included, one being a Class III-plus formula. The other would use the ‘higher of,’ but would base it on end-of-month four-week announced class and component prices instead of the two-week prior month advance pricing.

The hearing docket also contains four proposals on Class I differentials, including NMPF’s proposal to increase them in all locations by varying amounts as well as MIG’s proposal to lower them across the board by $1.60.

Two proposals from NMPF and National All Jersey will be heard to update milk component factors.

Six proposals will be heard on Class III and IV pricing formulas. Three are separate proposals from NMPF, IDFA and Wisconsin Cheesemakers to update processor credits, known as ‘make allowances,’ as well as three from Select Milk Producers on butterfat recovery, farm to plant shrink and nonfat solids yield.

In addition, the hearing scope includes four proposals on how dairy commodity products are surveyed, including NMPF’s proposal to remove 500-lb barrel cheese from the weekly survey, AFBF’s proposal to add bulk 640-lb block cheese and unsalted bulk butter, while California Dairy Campaign’s proposal would add mozzarella.

Dairy farmers can testify in-person at any time during the hearing, or virtually on Fridays. Beginning Fri., Sept. 1 and for each Friday thereafter until the hearing concludes, dairy farmers may testify virtually in 15-minute time slots beginning at Noon ET. There will be 10 slots for virtual testimony each Friday.

To be included, farmers must pre-register. The pre-registration for each Friday’s time slots will be available starting Monday of the same week at the USDA Hearing Website. For example, the link to testify on Fri., Sept. 1 will be available on Mon., Aug. 28. To submit exhibits for the record, email them to FMMOHearing@usda.gov by 8:00 a.m. ET on the day of testimony.

Those participating in the hearing in person should notify a USDA official upon arrival at the hearing. For additional information, contact Erin Taylor, Director, Order Formulation and Enforcement Division, USDA/AMS/Dairy Program at Erin.Taylor@usda.gov.

Does a watched pot boil? National Refuge proposal ‘paused’ in NW PA and SW NY; Fish and Wildlife says new draft coming

AUTHOR’S NOTE: National Wildlife Refuge designations and land protection plans are long-simmering recipes, so it’s important to keep eyes on the pot while the heat is presumed to be turned down. Will a watched pot boil? One thing to keep in mind is to look overseas at the Netherlands, where the government, thrown this week into disarray to where the farmer-citizen party may gain strength, has been using climate-based targets to begin pushing buyout or closure of an estimated 3000 farms. Dutch farms have been zoned for a range of production-cuts from 15 to 90% with options to sell their land to the government. The Dutch farms identified for the largest production cuts of 75 to 90% would obviously be economically unsustainable and therefore more apt to sell. These are the farms that are located closest to EU Nature Preserves that were designated decades ago. When I spoke with a Dutch dairy farmer last year about this, he explained that the nature they have has been built, improved, by the farmers, but those close to the network of EU preserves are in the current crosshairs. Yes, these are long-simmering recipes. Here in the U.S., Northwest Pennsylvanians are being told it will take decades to complete a land protection plan if a French Creek National Wildlife Refuge is eventually designated for the watershed by the U.S. Fish and Wildlife Service Director. They are told that farming can continue, that they want to ‘help’ local conservancy efforts and that only willing sellers would be pursued. That’s not how it went when the Erie Refuge was completed at the center of the French Creek watershed in the 1970s. Some saw farmland fall to eminent domain two decades after that Refuge was established.
Bottomline: Keep an eye on the pot, even if doing so draws accusations of claiming a tepid pot is about to boil. Every cook knows what happens when looking away. Here’s an update since the meeting between elected officials and the U.S. Fish and Wildlife Service.

By Sherry Bunting, Farmshine

MEADVILLE, Pa. – The U.S. Fish and Wildlife Service (USFWS) has “committed to a ‘pause’ and will draft a new proposal that could potentially limit the size and scope of a National Wildlife Refuge in the French Creek watershed,” according to a press release from Congressman Mike Kelly’s office.

The proposed refuge and concerns shared by farmers were first reported in the June 30 Farmshine, followed by a more detailed report in the July 7 edition.

Congressman Kelly and elected officials from affected counties met on July 6 at the Crawford County Courthouse in Meadville to discuss the proposed Refuge with USFWS representatives Vicki Muller, the project manager, and Mark Maghini, a realty chief.

This comes after the ‘public scoping’ phase where opposition and concerns were raised by farmers, members of Congress, county leaders, local residents, as well as questions about its necessity being raised by those involved in local land trusts and conservation efforts already operating in the watershed.

The ‘planned Refuge’ would create new federal ownership and oversight of lands in the watershed of nearly 800,000 acres along the 117-mile French Creek through portions of Crawford, Erie, Mercer and Venango counties, Pennsylvania and Chautauqua County, New York.

According to Congressman Kelly’s office, the USFWS acknowledged it did not properly engage and inform the communities of impact and will include elected officials in future planning.

“A pause on the proposed French Creek National Wildlife Refuge is absolutely necessary. Officials from the U.S. Fish and Wildlife Service have told us there is no official plan or size for this refuge, and I believe that’s exactly the problem — this has been a solution in search of a problem with farmers and landowners caught in the middle. The federal government does not need to have control of French Creek,” said Rep. Kelly in the statement.

“We all support a healthy and vibrant French Creek, but I believe local conservation efforts are already accomplishing what the USFWS is trying to do,” he noted.

Nothing to see here. Just go about your business…

Meanwhile, Maghini, the realty chief (land acquirer) for the Northeast region of the Fish and Wildlife Service indicated in an email to the Meadville Tribune that there is “no proposal,” pointing to a June 4 update at the special webpage for the project with these words highlighted in bold type.

He insists that the goal of the meetings and input-gathering this spring was to “identify whether there’s a role USFWS can play in the French Creek watershed.”

However, the agency’s own documents at the site show it already has a plan and has identified the next steps, which indicate it is already in the process of evaluating those public comments to develop a final proposal, which had a summer 2023 timeline.

Specifically, the “Schedule for Establishing the Proposed French Creek National Wildlife Refuge” on the second page of the May 9 FAQ document at the project webpage, is as follows:

1) Develop draft Land Protection Plan (LPP) and Environmental Assessment (EA) in the Spring of 2023;

2) Conduct public review and comment on proposal in the Spring of 2023; and

3) Evaluate the comments and develop the final plan for approval in the summer of 2023.

The customary procedure is for comments from the public scoping phase to be used when USFWS develops a land protection plan and environmental assessment. The ‘pause’ may extend this schedule to allow more time for the agency to evaluate the comments it received and to include elected officials in its planning.

Whenever a final plan is developed, the public then has 45 days to review and comment before it is ultimately left to the USFWS director, who has the sole authority to approve or disapprove a plan, according to the agency’s FAQ.

Residents tell Farmshine they hope a new draft provides more detail and a much smaller scope, but they also hope the ‘pause’ allows time for more public input on whether or not the Refuge designation is even needed.

The designation of the French Creek as 2022 River of the Year by Pennsylvania Organization for Watersheds and Rivers came largely due to the success of the existing local conservation efforts in promoting the health and biodiversity of French Creek in the first place, they say.

This brings the feeling that one can farm for generations, keep the working lands clean and natural, and then find out this can lead to being more, not less, vulnerable to having a Refuge designation with potential impacts for the future.

Pennsylvania Farm Bureau legislative director Nick Mobilia said as much to the Corry Journal: “I feel we have presented our issues with the refuge as positively as we can. We asked what USFWS thought was wrong with the waterway — they did not have any areas of concern.

“We as a local collective maintain French Creek and take pride in it — of course we are going to fight for it to be left as it is,” he said. “I think this was realized on (July 6) and (USFWS) will walk away from French Creek and focus on waterways that do need the government’s help.”

Will USFWS walk away? Doubtful.

Maghini, the USFWS realty chief for the region told the Meadville Tribune Friday (July 7) that the agency “looks forward to working with local officials once a plan that incorporates local feedback already collected has been prepared.”

Interestingly, the title of the FAQ document on the project webpage refers to the project as a “Proposal to Expand Refuge Lands in the French Creek Watershed.” 

This reference to “expansion” is significant. At the center of the land protection plan “areas of interest” on the USFWS conceptual map (above) lies the already existing Erie National Wildlife Refuge (shaded pink within the green). Previously managed by Muller, the existing Erie National Refuge encompasses 8,777 acres of the 798,000-acre French Creek watershed.

At public meetings this spring, a farmer recalled his family’s farmlands eventually falling into eminent domain in the 1970s – more than a decade after private lands within what is today the Erie National Wildlife Refuge were originally designated by the USFWS in the late 1950s. 

According to local newspaper accounts, Muller responded by telling the crowd that the USFWS “doesn’t do that anymore.”

The other significant aspect of ‘expanding’ an existing refuge vs. declaring a new one is that the Inflation Reduction Act provided climate resiliency and biodiversity funds for 2023 through 2026, including more than $121 million to the USFWS for restoration, rebuilding and expansion of existing wildlife refuges and $125 million for endangered species recovery.

The latter identifies 32 initial plant and animal species to be recovered “wherever found.” One, for example, is the snufflebox mussel with one area shown on its map as the French Creek watershed.

Will the public get more input? Will it help?

USFWS documents explain that when land protection plans are drafted and approved, they include land acquisition timelines that follow a “Landscape Conservation Design to ensure actions contribute to the landscape-level vision.”

Will a ‘pause’ give farmers, landowners and communities more say in the vision for their landscape, one they want to retain locally? Will the USFWS commitment to include elected officials in the planning happen before or after the new draft is presented?

Revamped ‘live text’ at the special webpage for the proposal notes that the USFWS review of public comments in April and May boil down to the following beliefs held by residents that USFWS says it agrees with: 

1) Residents have a deep affection for French Creek; 

2) They believe maintaining use of prime agricultural lands is important; 

3) They value the rural character of the watershed and want to ensure its persistence; and 

4) They value local land trusts within the community and trust them in their land protection efforts.

USFWS states further that a National Refuge designation is what authorizes the agency to pursue the land acquisitions from willing sellers and that it does not detail how USFWS would manage the lands it acquires through fee-title or easement. 

USFWS also states that it does not fund local conservation efforts because it must show a dollar of federally-acquired land for every federal dollar it spends.

However, within this two-page “Proposal to Expand Refuge Lands,” the agency lists goals for “new refuge lands” (beyond the existing Erie National Refuge) that would allow the agency to “protect and manage the French Creek and its tributaries and wetlands.”

It also purports to “help” local conservancies by adding federal acquisitions to local acquisitions since none of these entities have access to unlimited funds. The only way it can “help” is to federally acquire land.

The U.S. Fish and Wildlife Service is a Bureau within the U.S. Department of Interior that operates in a quasi-independent fashion, having federal authority to establish and manage protected lands within its National Wildlife Refuge System, and to complete approved land protection plans over subsequent years, through its Land Acquisition and Realty division.

According to that division’s section of the USFWS website, funding for land acquisition comes from the Migratory Bird Conservation Fund through federal Duck Stamps and import duties on arms and ammunition as well as through the Land and Water Conservation Fund from offshore oil and gas leases.

In 2021, at the start of the Biden Administration, the USFWS updated its “Climate Adaptation Strategy” to be a framework that is part of the Administration’s “U.S. Climate Resilience Toolkit.” 

Several documents available at the USFWS website explain that this toolkit has now equipped USFWS to “take immediate action to build ecosystem resilience in the face of climate challenges.”  

As noted in the previous Farmshine articles, this is a process that moves at a snail’s pace — with or without a ‘pause.’ 

The ‘pause’ is expected to move the project from the front-burner to the back-burner — for now — amid the public heat surrounding it, but this doesn’t mean it is off the stove.

National Wildlife Refuge designations and land protection plans are long-simmering recipes, so it’s important to keep eyes on the pot while the heat is presumed to be turned down. Does a watched pot boil?

-30-

Photos by Sherry Bunting

Part One: What’s driving rocky road for milk prices?

The stunner in the USDA FAS data is the U.S. imported 51% more Whole Milk Powder (WMP) in the January through May 2023 period vs. year ago. Looking at import volumes vs. All Milk prices, Fig. 1 shows the pattern: From 2008 to today, whenever there is a period of high farm milk prices, WMP imports increase, and farm milk prices fall. While cheese imports are down 3% YTD, non-cheese dairy exports are up 80% for a 9.2% total increase based on straight volume. Retired co-op executive Calvin Covington recently figured the January through April imports up 15% on a total solids basis. Graphic by Sherry Bunting compiled from USDA FAS and NASS data

— WMP and other imports accelerate, cow-less lab-protein analogs become ‘extenders,’

— Class I sales keep declining, fresh Italian cheese production down, inflation drives CPGs to reduce unit-sizes,

— RNG-driven dairy construction accelerates concentrated growth in cheese-heavy Central U.S.

By Sherry Bunting, Farmshine June 30, 2023

EAST EARL, Pa. — Current milk futures and dairy commodity markets have turned sharply lower and signal a rocky road ahead for farm level milk prices. Because of the lag times built into federal milk pricing, the most recent steep losses in spot cheese markets will hit the Class III price and create more Class I mover losses via the ‘average of’ method to hit milk checks in July, August and September. 

Factors driving this include: declining Class I sales and fresh Italian cheese production, inflation-driven unit-size shrinkage, two months of reduced dairy exports and five months of increased dairy imports, and the advertising of cow-less lab-protein analogs as ‘extenders’ for food processing.

The May Milk Production Report confirmed that the Central U.S. is, indeed, “awash in milk.” Part two of this series will zoom into the geographic shifts in the concentration of milk growth, driven largely by Renewable Natural Gas digester projects for the California RNG gold rush. Much of the new dairy construction in the cheese-heavy Central U.S. is focused on manure to energy, not necessarily on milk and cheese to consumers.

The Production Report was released after the futures closed on June 21. In the next four trading sessions from June 22 through 27, Class III contracts for July through September lost $1.50 per cwt, on top of previous losses of more than $2. 

By June 28, the expiring June Class III milk futures contract was at $14.92, and at $14.91 in the June USDA announced.

The ‘market’ has simply ignored USDA’s May 30 announcement that the government will bring in a ‘game changer’ to purchase 47 million pounds of cheese for food banks and schools as block and barrel cheese plunged to $1.31 and $1.39 per pound, respectively, by Tues., June 27.

USDA confirmed last week that the first round of its bid solicitations for the first phase of the 47 million pound cheese purchase won’t open until October. Bids and deliveries will come in stages from fourth quarter 2023 through mid-2024. 

This means cheap milk will make cheap cheese, which could get even cheaper if inventories build in anticipation of selling that cheese at a tidy profit into the seasonal demand increases that begin in October, along with these announced government cheese purchases. (Who needs a make-allowance raise with this game in town?)

For the past several weeks, USDA Dairy Market News has been reporting spot loads of milk in the Central U.S. selling as much as $11 per cwt below the Class III price. DMN also reports milk from the Central U.S. growth region is moving farther to find a home. We are also hearing from readers about substantial milk being dumped in the Midwest, while a few independent dairies in Minnesota, one milking over 1000 cows, have been told by their creamery that their milk is not needed after schools close.

May milk production, nationwide, was up only 0.6% from a year ago. The 24 major monthly states were up by 0.8%. Milk cow numbers did not grow from April to May and are running just 13,000 head above year ago. This modest increase comes on the heels of no net gain in milk production for 2022.

All year, the monthly USDA World Ag Supply and Demand Estimates (WASDE) kept increasing the 2023 U.S. milk production forecasts, based on what it said are ‘more milk cows and less output per cow.’ The most recent WASDE walked that production forecast back a bit, but still expects U.S. dairies will milk an average of 9.415 million cows in 2023. 

Then, somehow, the May Production Report pegged the number of milk cows on farms at 9.424 million head, even after the loss of 18,000 milk cows in a fire in west Texas in April. This is how tight the figuring has become on what we are told today is a surplus of milk and a lackluster demand.

The idea of a milk surplus that is big enough to drive these current price losses does not line up with USDA’s Jan. 1 cattle inventory report. So, in May, the WASDE began to walk it back, noting higher feed costs, reduced milk margins and higher beef cattle prices will slow the flow of milk.

Where are the cattle coming from? The Jan. 2023 inventory showed milk cow numbers were virtually unchanged from Jan. 2022 at 9.4 million head. The number of dairy heifers over 500 pounds was down 2% at 4.337 million head — the lowest number since 2006. Within that heifer number, expected calvings from Jan. 1, 2023 to Jan. 1, 2024 were also 2% lower than for Jan. 2022 to Jan. 2023. The next semi-annual cattle inventory report will be released in three weeks on July 21.

The Report’s smaller dairy replacement inventory is believable given the fact that offerings have been selling $300 to $500 per head above year ago levels, and the few weekly dairy cattle auctions throughout the U.S. have seen offerings down 30% below year ago… until June, when prices came under pressure on a suddenly increased offering at auctions over the past two weeks. 

Meanwhile, dairy cow slaughter rates are also increasing, according to USDA, especially in the Midwest and Southwest, up 31 and 47% above year ago, respectively.

While the WASDE has forecast per-cow output to fall by 55 pounds per cow per month in 2023, the May Production Report pegged an 11-pound per-cow per month increase.

This means, it took just 13,000 more cows nationwide, and just 11 more pounds of milk output per cow per month to flip the switch to sharply lower milk prices based on – suddenly — too much milk? (Geographic concentration of milk growth plays into this equation, and we’ll discuss that in Part Two.)

In Part One, we look at the other supply and demand factors that are having a direct impact on where farm level milk prices are headed. These factors fill in the gaps left by the perplexing and contradictory sets of USDA dairy data.

I.               Fresh fluid milk sales and fresh Italian cheese production both declined, pushing more available spring-flush milk into storable products.

Fluid milk sales January through April were down 2.8% from a year ago, and as bottlers slowed school packaging ahead of summer recess, the June 5th Dairy Products Report showed April production of fresh (made to order) Italian cheeses also declined 2.6% vs. year ago.

Meanwhile, butter production was down 4.9% while nonfat dry milk production increased just 1.9%, and skim milk powder production was down 22.4%. This put more of the available ‘spring flush’ milk into production of American cheese, up 2.3% vs. year ago in April, and the accompanying dry whey and whey protein concentrate production up 1.7 and 7.2%, respectively. 

Record volumes of dry whey and cheese have been coming to the daily CME spot auction, driving down the spot prices that drive the National Dairy Product Sales Report prices that are then used in federal class and component pricing formulas.

II.            Inflation pressures consumer demand, but inventories are not burdensome.

The May Cold Storage Report released on June 23 was a head-scratcher. Despite the ramped up American cheese production in the Dairy Products Report, the Cold Storage Report showed both the total amount of cheese in inventory, and the amount of American cheese in inventory, are both actually down 1% from a year ago at the end of May, while butter inventory was up 14% against last year’s higher-price-driving short supply.

Meanwhile, producers in the Midwest are being told that milk co-ops and buyers are facing cheese sales declines and that there’s not enough capacity to process all the milk now being produced in the region, with the existing capacity also experiencing labor and transport disruptions.

Dairy demand has stagnated, the analysts say, after months of high inflation. The May dairy consumer price index (CPI) was more bearish than the overall CPI. Dairy CPI was up 4.6%, with cheese up 3.6%, ice cream up 8% and other dairy products up 9.3% while whole milk decreased 3.4% and other non-whole milk increased 0.6%.

Inflationary pressure is driving some consumer packaged goods companies (CPGs) to trim unit-sizes for an appearance of stable consumer pricing. For example, we see unit-size shrinkage in cheese packages and slices. Not all American cheese slices today are 8 ounces, some are 6. Such moves effectively ration demand. 

III.            The stunner is dairy imports, up 9.2% with Whole Milk Powder imports up 51% year-to-date.

Looking at import volumes vs. All Milk prices, the pattern is clear (Fig.1). From 2008 to today, whenever there is a period of high farm milk prices, Whole Milk Powder (WMP) imports increase, and farm milk prices fall. 

WMP is basically farm milk from another country, in bulk dried form, not a specialized product. It can be used in processing virtually any dairy product, containing all of the milk components — both fat and skim solids.

From December 2022 through April 2023, the U.S. imported the highest percentage of dairy production equivalent since 2016. And there is more milk equivalent comparison today than in 2016. The National Milk Producers Federation’s monthly market report confirmed this. 

Then May imports worsened this trend. 

Digging into the June 12 USDA Foreign Ag Service (FAS) Import Circular, the U.S. imported 80% more non-cheese dairy products from January through May vs. year ago. At the same time, cheese imports were down 3.3%. Combined, the total cheese and non-cheese imports were up 9.2% vs. year ago.

But the stunner in the data is the U.S. imported 51% more WMP in the January through May 2023 period vs. year ago. 

It’s no wonder that the USDA Dairy Market News reported on June 15 that, “Dry whole milk processing (in the U.S.) is limited, despite hearty milk volumes.” 

The report went on to say that even as seasonal milk output recedes “market contacts suggest dry WMP market tones may remain steady (at the current lower price levels) due to lighter demand.”

Not surprising, given the U.S. imported more WMP in May (550,000 kg) than for any month since April of 2020. WMP was imported at a record-setting pace during the pandemic while milk was being dumped in the U.S. and production-base-programs were tightened on U.S. dairy farms by milk cooperatives and buyers. 

As the cumulative 2023 WMP imports accelerated in May, milk prices are set to take the sharp turn lower.

The year-to-date imports of butter, butterfat and butter oil are also well above year ago as part of that 80% increase in non-cheese imports January through May 2023 vs. year ago.

The June WASDE raised dairy import forecasts, yet again, especially on a fat basis, and it again lowered dairy export forecasts. The Report sees butter and nonfat dry milk (Class IV) continuing to sell stronger on better demand, while demand and prices for cheese and whey (Class III) are further reduced. 

This combination reduced the WASDE forecast for the 2023 All Milk price to $19.95, down 55 cents from the May forecast. Part of this is the Class IV over III divergence that is substantially lowering the Class I fluid milk price under the ‘average of’ method, which took more than $1.00 off the advance Class I price mover for July, announced last week at $17.32. It would have been $18.34 using the previous ‘higher of’ method.

IV.          Lab-created dairy protein analogs are advertised to processors as ‘extenders.’

Another emerging factor is the lab-created dairy protein analogs, which are the excrement of microorganisms that have been bioengineered with bovine DNA. These proteins are advertised in dairy food and manufacturing magazines as carbon-footprint-lowering, interchangeable ‘extenders’ for production of cheese, ice cream and other dairy foods.

The companies that are ramping up this fermentation-vat-lab-protein are doing limited consumer marketing. Mainly, they pursue a B2B model (business to business, not business to consumer) and try to capitalize on ESG scoring benefits based on who-knows-what-calculations that large processors are seeking as they navigate the investment, credit, and retail shelf-space ESG decisions up and down the supply chain.

No one knows how much lab-dairy-protein is being used at this time — or in what brands of dairy products — because these proteins do not have to be labeled, and they are not part of any dairy market or production report.

The Bioengineered Food Disclosure Law was passed by Congress in July 2016, and USDA established the national mandatory standard for disclosing foods that are, or may be, bioengineered in December of 2018. This Standard was implemented on Jan. 1, 2020 with mandatory compliance for all food manufacturers by Jan. 1, 2022.

According to USDA, the Standard defines bioengineered foods as “those that contain detectable genetic material that has been modified through certain lab techniques and cannot be created through conventional breeding or found in nature.”

The lab-dairy-protein-analogs are the harvested excrement of fermentation-vat-grown bioengineered yeast, fungi and bacteria, so BE labeling is not required due to the ‘detectable genetic material’ loophole. The modified genetic material is in the microorganisms, not their excrement.

-30-

Northwest PA farmers fear future land-grab as U.S. Fish and Wildlife proposes Refuge designation for 798,000 acres of French Creek watershed

PREVIEW – By Sherry Bunting, Farmshine, June 30, 2023

WATTSBURG, Pa. — Kevin and Amanda Bush are fourth generation dairy farmers with their children Ava, 17, Clara, 6, Jarrett, 5, Georgia, 1, and 110 milk cows. On an early June day, unseasonably cold even for Erie County, Pennsylvania, a visit to the Bush Family Farm shed light on farmers’ concerns about a U.S. Fish and Wildlife Service proposal to designate 798,000 acres of French Creek watershed as a National Wildlife Refuge. Potential land acquisitions could begin a year from now if approved by the USFWS Director later this summer. Mark Muir from Erie County Farm Bureau, who raises hay and livestock, and Brian Young, whose extended family operates a nearby seventh generation farm were part of the discussion of the proposed protection area that would stretch 117 miles from Chautauqua County, New York south through Erie, Crawford, Mercer and Venango counties, Pennsylvania. The region is home to farms and other businesses that are the lifeblood of rural towns and counties. They use conservation practices and a lot of grazing and haying, with a vested interest and pride in their stewardship and relationships with existing conservation efforts. 

On a map showing land protection ‘areas of interest,’ whole farms are included, not just setbacks (see map in main story below). This includes many dairy farms ranging from small herds managed by young next-generation farm families, like the Bushes, to larger farms with multiple generations of families involved. USFWS wants to purchase land or use permanent easements for whole farms. ‘You can still farm it,’ they say. But when specific questions were brought to an April meeting, the locals came away with very few answers. They anticipate another meeting in July. 

Why are farmers concerned? They fear future use of eminent domain and farming restrictions as dominos start to fall. A National Refuge designation with Land Protection Plan, is perpetual. They fear the loss of rented ground to feed their cows. They worry about their towns and counties. They want to know the minimum goals of the project so they can have an intelligent conversation with USFWS. They have asked for scientific studies to be shared that show how the freshwater mussel population and other aquatic life are actually doing today vs. 10, 20, 30 years ago.

It feels like the start of what could become a gradual 30 x 30 land grab. Surely, if this was happening in agricultural communities of southeastern Pennsylvania along the Susquehanna River in the Chesapeake Bay watershed, instead of northwestern Pennsylvania in the French Creek watershed, there would be much more attention paid. See main story below as published in July 7, 2023 Farmshine, and stay tuned as we follow this developing story.

They say National Refuge for mussels will move at snail’s pace, but farmers see muddied water ahead

MAIN STORY – By Sherry Bunting, Farmshine, July 7, 2023

WATTSBURG, Pa. — The rural French Creek watershed is in the sights of the U.S. Fish and Wildlife Service for a proposed National Wildlife Refuge that could span nearly 800,000 acres, stretching 117 miles from the headwaters in Chautauqua County, New York across the Pennsylvania border through Erie, Crawford, Venango and Mercer counties.

Meetings this spring in Meadville and Edinboro were part of the ‘public scoping’ phase. They were packed with citizens and fraught with questions, deep concern and objections. 

An initial public comment period ended May 19.

From the Southwest corner of New York through the Northwest corner of Pennsylvania, the French Creek river and watershed runs through rural communities where farming is the lifeblood. If this potential land-grab were happening in southeastern Pennsylvania in the Chesapeake Bay watershed, more attention would be paid to the concerns of the farmers and communities.

Vicki Muller, the proposed Refuge’s project manager, told local television station FOX-66 that the U.S. Fish and Wildlife Service (USFWS) is “looking to protect and preserve more wildlife habitat within the French Creek watershed, so this plan is just the beginning stages of that.”

Mentioned were freshwater mussel species, said to be the only populations east of the Mississippi, along with several species of fish, wetlands, and migratory waterfowl.

Land acquisitions are about a year away, Muller confirmed.

Farmers and other community members, along with managers of existing conservation efforts, say federal land acquisition is not necessary to meet environmental goals because those who are living, working, farming in the region already work with local conservationists to manage the land in ways that have been recognized for success.

French Creek was named Pennsylvania’s “River of the Year” in 2022. 

Opponents of the Refuge argue that its designation could place federal regulation on private landowners for perpetuity. They say an accompanying Land Protection Plan (LPP) could take properties and money off local tax rolls, move land ownership away from local residents, and take products generated on the farmland away from local communities, weakening the region’s economy and food security.

To top it off, USFWS could offer no evidence that this would improve — at all — the status of French Creek and its aquatic life, nor any evidence that either are in trouble.

USFWS is currently in the process of reviewing public comments and stakeholder feedback and is developing a final plan for approval by the USFWS Director later this summer, according to a Q&A document at the webpage devoted specifically to the French Creek proposal at https://www.fws.gov/project/evaluating-new-refuge-lands-french-creek-watershed. 

A June 4 ‘Public Scoping Recap’ is also provided at this webpage, stating the proposal is not yet an official proposal because it is still in the ‘public scope and biological environmental assessment’ phase.

The webpage indicates that the framework would be built after they get the buy-in, after they get the National Refuge designation and LPP approved, and after they complete the biological environmental assessment. That’s when officials say they can answer the probing questions of locals about environmental and land acquisition goals.

Isn’t that putting the cart before the horse?

One of the strategies being used here is to protract the conversation and soothe public concern with assurances that the Refuge to save mussels will move at a snail’s pace.

Essentially USWFS is looking to designate land now for decades of acquisition and that it will answer specific questions as the process moves forward working collaboratively to refine the plan after the designation and plan are approved.

Such circular talk makes farmers and landowners skeptical, uneasy.

Within the “land protection areas of interest” on the ambitious map, there are both small and larger farms, many of them dairy farms as well as beef cattle, crop and produce growers.

“I started looking at the map, and I see I am an area of interest. Everything I own is an area of interest,” said Mark Troyer, a potato, corn and wheat grower, in an on-camera interview during the Edinboro meeting. “I think we can work and live hand-in-hand (with wildlife) and have been doing a great effort. We’ve already been doing a great job.”

Concerns about eminent domain were specifically raised. Muller stated this will not happen. 

Landowners are not convinced. They want to know the endgame. 

They want to know what happens once there is an approved LPP with specified land acquisition timelines. What happens to their farms if they are eventually surrounded by acquired land? What happens to the farms outside of the areas of interest that will find themselves next to a National Refuge? What is the ultimate land acquisition goal?

What are the actual environmental goals, and why does the federal government need to acquire the land to meet those undisclosed goals, instead of supporting existing local conservation efforts that show measurable success?

They share the concern that once the designation and LPP are approved, this could take on a life of its own… forever.

A pristine view across the road from the Bush Family Farm. Behind the trees is French Creek. The Bushes wonder why land acquisitions are needed. Farms throughout the watershed do a good job. They wonder what will happen to their farm if there are willing sellers up and down the road from them…

According to the USFWS Q&A, the land protection plan will take decades to complete as the number of willing sellers and the availability of funding will determine the timeline.

With that in mind, U.S. Congressmen Mike Kelly (R-Pa.) and Nick Langworthy (R-N.Y.), whose congressional districts cover the “areas of interest” in the draft proposal, along with U.S. House Ag Committee Chairman Glenn ‘G.T.’ Thompson (R-Pa.), led a letter calling on the USFWS to reconsider federal designations on private land.

In the letter, the members of Congress recognize that a healthy, vibrant ecosystem along French Creek must continue to be protected, but also that local farmers and residents are better suited than Washington bureaucrats hundreds of miles away to dictate how this land is best protected.

Mark Muir with the Erie County Farm Bureau grows hay and raises livestock in the area. He has been involved in the meetings, asking questions at the front end of this proposal.

Farmshine met in June with Muir at the Bush Family Farm outside of Wattsburg in Erie County. He was joined by Kevin and Amanda Bush as well as Brian Young, whose extended family operates a nearby 7th generation farm.

The Bush farm has been in the family since 1939. French Creek borders it, surrounded by grasses across the road from the dairy barn and hillside grazing paddocks. The Bushes also rent crop ground in the watershed.

They and others are concerned that once a final plan is developed and approved later this summer, land acquisitions from willing sellers could eventually morph into a land-grab that won’t stop until all of the “areas of interest” are federally owned or controlled by the USFWS.

The designation of the land as a National Wildlife Refuge and the approval of an LPP would be the first concrete steps.

“We are told there is nothing set in concrete yet,” says Muir, “But we had many questions they couldn’t answer at the meetings. We tried to talk to them about farm BMPs (best management practices), but they didn’t understand the concept.”

Because the USFWS is still in the ‘public scoping, comment review and final development’ phase,’ officials won’t engage in land use questions or what-if scenarios. They don’t answer questions that help farmers understand the ultimate impact because they say that completion of the Refuge would be “decades away.”

“Decades away” is really tomorrow for most farmers who continually look ahead at their operations and land use, making plans for future generations.

Mark Muir (right) and Brian Young stand across the road from Bush Family Farm by a section of French Creek that runs parallel. This is just one small part of what could be a massive target for federal land acquisitions and easements if the watershed is designated a National Refuge.

“At the end of the day,” says Young, “Fish and Wildlife can target any wildlife and the ecosystem areas that an environmental assessment deems necessary. They are not like the BLM or NRCS. The USFWS is comparatively small and does not have the cross-correlation to agriculture.”

Furthermore, land acquisitions are funded by duck stamp sales, land access fees, and other sources of revenue that make USFWS less reliant on tax dollars to use their authority. In other words, Congressional oversight — from an appropriations standpoint — is lacking.

If a final plan and Refuge designation are approved, the gradual creep of land acquisitions would begin, giving USFWS oversight of current working lands that could affect the fate of farming in the region, in particular dairy and beef cattle.

Without data and without answers, this becomes “a slippery slope with no guard rails,” says Muir. “We want to be objective about it, and to have those conversations at a July meeting. We need certain information to have a meaningful conversation so we can see if and where we might be able to work together.”

Meanwhile, Kevin and Amanda and their four children milk 110 cows and raise their youngstock. They are a small family dairy on land that the Bush family has been farming for 85 years.

There is not only a legacy here, but also progress as they have implemented many BMPs, just as other farms have throughout the region.

Muir notes that NRCS funding, and other cost-shares, don’t seem to flow as much in the Northwest direction of the state. 

He says BMPs on farms could improve even more with cost-sharing and a productive dialog, which is preferable to a multi-decade federal plan to acquire the land.

“If this is supposed to be to save the freshwater mussels, and they have these dollars to spend, why not try other approaches first?” Amanda wonders, adding that they could promote BMPs that farms can do even better than what they are already doing, and cost-share some of that. “It would go a lot farther instead of designating a Refuge, buying up land, and disrupting family farms, local towns and their economies.”

“We do no-till and minimum tillage here. We do cover crops wherever we can, and we are working now already with the County Conservation District,” Kevin adds.

Bottom line, these and other young farmers want to continue farming and producing food for their communities. They are part of these rural communities where cows and crops, grazing and haymaking, youth programs and showing at the county fair are part of the fabric.

Maybe it’s more important to identify the rural community fabric that is at stake — the younger generations who want to continue. As farm families of all sizes, they are accustomed to working with USDA, NRCS, county conservation districts, local conservation efforts that all have connections to agriculture, so they speak the same language.

But when Fish and Wildlife makes its entrance with a draft proposal for a National Refuge of immense proportions across so many miles, acres and counties — having no crossties to agriculture — that’s a scary place for any farm family to be, and it can lay threadbare the fabric of the communities beyond the farms.

To be continued

AUTHOR’S NOTE: A USFWS National Refuge designation and Land Protection Plan includes acquisition timelines and a “Landscape Conservation Design” to “ensure actions contribute to the landscape-level vision,” according to USFWS documents. USFWS is a Bureau within the Department of Interior and operates in a quasi-independent fashion, having federal administrative authority to establish and manage such refuges and complete them over time with its own sources of funding. In 2021, at the start of the new Administration, the USFWS updated its “Climate Adaptation Strategy” to be a framework that is part of the Administration’s “U.S. Climate Resilience Toolkit,” equipping USFWS to “take immediate action to build ecosystem resilience in the face of climate challenges.”  (One thing to keep in mind is to look overseas at the Netherlands, where the climate-based land-grab is in full swing. Farms have been ordered to cut from 15 to 90% of their production or sell their farms to the government. The farms identified for 75 to 90% production cuts to be economically unsustainable are those that are closest to the EU Nature Preserves designated decades ago.)